Health Insurance for Expats

Health Insurance for Expats

Do I Need Health Insurance for Expats?

If you want help covering the costs of your medical expenses while living abroad then, yes, you’ll need international health insurance for expats. It may also be required by the government of your destination country. For example, Portugal requires expats to carry valid health insurance that covers necessary medical expenses such as urgent care and repatriation.

While it’s not always required, expat health coverage is usually a good idea. It helps to ensure that you can get quality medical attention in a variety of scenarios at an affordable price. For example, in the unfortunate case that you’re involved in a serious car accident and need emergency care, it will often help to cover the costs of your hospital stay, any required surgeries, rehabilitation, and repatriation (if necessary). 

Further, if you were to develop a serious illness like cancer, health insurance can help to cover the costs of chemotherapy or radiation therapy, specialist visits, lab tests, and other care you would need. 


What Is Health Insurance for Expats?

Health insurance for expats refers to the health insurance plans that help cover the costs of medical services abroad (and in the U.S., for some plans). It’s comparable to the coverage you would have from a health insurance provider in the U.S.—you can access emergency assistance, private hospitals, doctors, nurses, and prescription medications in foreign countries, and your insurance will help to cover the costs, in many cases. 

Note that expatriate health insurance is different from travel insurance. Travel insurance is designed for people taking shorter-term trips versus living abroad long-term. 

How Does Health Insurance for Expats Work? 

Here’s a look at the cornerstones of expat health insurance from policy limits and coverage areas to pricing. 

Maximum Limits

Each plan will have a maximum annual plan benefit which is the most the plan will pay out during the annual policy period. Additionally, the plans often have dollar limits on specific benefits (e.g. rehabilitation treatment, nursing at home, and accidental death). These limits may be on a “per event” or “per year” basis. 

Some insurance providers do offer unlimited coverage, although it’s more of an exception than the rule.  

Beyond the policy dollar limits, the benefits included in expat health insurance policies will vary. For example, a higher-tier plan may cover preventative care while a lower-tier one doesn’t. Further, some insurers may cover vision care while others don’t. The availability of add-on plans like outpatient, maternity, and dental coverage can also vary depending on the provider, policy, and applicant. 

Coverage Areas

Insurers may offer various coverage area options. For example, Allianz Care offers worldwide coverage plus worldwide coverage excluding the U.S. and coverage for Africa only. The coverage area you choose will impact your pricing. 

Costs

Once you find the expat health insurance policy with the right benefits and coverage for your situation, a quote can help you understand the costs. When reviewing quotes, look for the annual and monthly premium prices, deductible options, annual plan limit, and coinsurance or copays that will apply. You can often choose a deductible amount which will lower your premium.

Medical Providers

When it comes to medical providers and facilities, expat health insurers typically have established networks. When you use providers from your insurer’s network, it often comes with perks like seamless billing. That said, most companies will let you choose any medical provider you want as long as they’re licensed and operate in a covered country.

Billing

The way your insurer covers your bills can vary. In some cases, you’ll be required to pay the medical provider upfront and submit the bill to your insurer to get reimbursed. In other cases, you may need to notify your insurer about a medical service before your appointment so they can coordinate with the medical provider and settle the bill directly. 

You may need to give your insurer a specific amount of notice to get a bill covered upfront—such as five days notice before seeking care. 

The specifics of expat health insurance plans can vary greatly from one provider to the next. While the common terms and conditions have been covered here, be sure to read the fine print from the companies you consider. 

What Does Health Insurance for Expats Cover?

The coverage provided through health insurance for expats varies from one provider to the next. However, all the plans we reviewed included inpatient services—care that requires you to be admitted and spend at least one night at a hospital or other type of medical facility. Beyond that, insurers vary in their offerings of benefits like outpatient care, preventative care, vision, dental, maternity care, life insurance, and more. Some offer multiple plans with varying levels of benefits, while others offer base plans with add-on coverage packages. 


Health Insurance for Expats Cost

Costs for expatriate health insurance (without U.S. coverage) are most influenced by your age and level of coverage. To give an idea of how costs vary, we collected quotes for both 35- and 65-year-old U.S. residents living in Mexico. 

35-Year-Old Expat

Monthly premiums ranged from $179 per month up to $476 per month for a 35-year old U.S. resident living in Mexico, based on our research. But cost can swing widely depending on the features you choose. 

For example, the Allianz basic plan (Care Core) costs $179 per month for a 35-year-old and has an annual maximum benefit of $2,500,000. On the other hand, an Elite Xplorer Essential plan from GeoBlue costs up to $476 per month, but has an unlimited annual maximum benefit and covers emergency outpatient care (the Care Core plan from Allianz does not). Both plans have a $0 deductible. 

You may also choose to increase your benefits by adding coverage. Allianz priced add-on coverages as follows:

  • Maternity coverage: From $66 per month
  • Outpatient coverage: From $106 per month
  • Dental plans: From $76 per month
  • Repatriation plans: From $11 per month

65-Year-Old Expat

If you’re a 65-year-old U.S. resident moving to Mexico, Allianz Care’s plans start at $583 per month with a $0 deductible and 2.5 million annual maximum benefit. An Elite Explorer Essential plan from GeoBlue costs up to $2,312 per month. It also has a $0 deductible, but provides an unlimited annual benefit and covers emergency outpatient care. Prices are precipitously more expensive the older you are because insurance companies expect you to more frequently use your plan. 

Allianz priced add-on coverages for a 65-year-old as follows:

  • Maternity coverage: Not available
  • Outpatient coverage: From $308 per month
  • Dental plans: From $76 per month
  • Repatriation plans: From $11 per month


Popular Health Insurance Companies for Expats

Now, let’s take a look at some of the most popular health insurance companies for expats. 

Insurance Companies Insurance Marketplaces
Azimuth Meridian International Citizens Marketplace
William Russell   
Trawick International   
Safety Wing   
NOW Health International   
Seven Corners Liason Majestic   
AXA Global Healthcare   
Bupa Global   
A Plus International   
AIA Group   
Now Health International   
Expacare Global Healthcare   
Integra Global   

Frequently Asked Questions

  • The cost of expat health insurance can vary greatly depending on your age, coverage area, benefits, deductible amount, and maximum limits. In our research, the monthly premium costs for plans with a $0 deductible ranged from $197 to $904.

  • Yes, you can get U.S. health insurance if you live abroad. Many expat insurance providers offer coverage in the U.S. as well as in foreign countries. However, when plans include coverage in the U.S., they are more expensive.

  • Expats are not required to carry U.S. health insurance. While it was previously mandatory for Americans who spent at least 36 days in the U.S. during a given calendar year, that requirement ended in 2018.

  • Expat health insurance can help to cover the costs of medical services in foreign countries. It often covers inpatient care including hospital stays, physician visits, surgeries, lab tests, physical therapy, transplants, and more. Additionally, some insurers offer coverage for outpatient care, preventative care, dental, vision, and more.


Reframe pandemic preparedness as global health insurance

Reframe pandemic preparedness as global health insurance

The headlines above the previous several months have been about a scary pathogen, considerations about vaccine availability, and what policymakers are doing to prepare ought to this turn into a common pandemic. No, these are not revisiting the news three a long time back. Fairly, the modern headlines about H5N1 Avian influenza circulating in mammal populations are much more reminders that novel pathogens, pandemics and biothreats are here to continue to be. 

The new Congress has an prospect to reinvest in the nation’s health and fitness infrastructure and greater place the country for the subsequent pandemic. This signifies, first, putting politics aside and, next, on the lookout to fortify pandemic preparedness. Whilst the former might be difficult, looking to advance the latter may well offer a auto to accomplishing better preparedness outcomes for our nationwide safety, economic prosperity and the region as a complete.  

According to the International Monetary Fund, the COVID-19 pandemic could cost the international economic system upwards of $12.5 trillion dollars by means of 2030 — a simply staggering amount of money of funds. With the globe heading to additional “zero sum” results as The Economist indicates, obtaining intelligent techniques of investing at home and making certain economic resilience will lead to not just far better development, but stronger development. 

It is fitting that policymakers converse of prescribed drugs and biotech now in the identical breath as semiconductors and other large-tech provide chains. They too are essential motorists of economic power, though also vital to our nationwide stability. For pandemic preparedness, this signifies hunting at crucial investments not as sunk prices, but as an coverage coverage that will, inevitably, be drawn on in the long run, no matter if artifical or pure in origin.  

Too frequently Congress has seen pandemic preparedness as a luxury at best or basically a sunk expense at worst — a little something that can be eradicated when the risk or menace is lowered or gone. This has found our country lurch from disaster to crisis, accelerating investing in the experience of an emergent condition only to cut down the costs or even zero out paying once the menace has passed. This inconsistent funding is mirrored in our reaction to novel conditions — small is carried out at 1st and then every thing is done all at at the time. This is a high-priced and dangerous technique to disorder administration. Even even worse, if we start off to see pandemic preparedness and response as a result of a political lens, we become divided on an situation related to the fundamental wellness of our country — and our skill to protect ourselves. 

As a starting issue, bad coverage provokes scattered responses and — irrespective of important attempts to the contrary — uncoordinated responses. We have the classes learned, irrespective of whether from SARS, Ebola, Swine Flu, H5N1, and now COVID-19 — the problem is not a scarcity of clever concepts, it is a scarcity of political will and a necessary framework. We have to have to look at pandemic ailment not as a collection of isolated incidents or mishaps but as a very long-phrase management problem that does, from time to time, need an elevated response.  

The begin-quit, all-in or all-out pandemic preparedness method sends the wrong alerts to the private sector which, though not wholly reliant on the federal government, does glance to the federal government for course and regular investment for stockpiling and producing. We are not suggesting that the government subsidize industrial growth, but that commitments are produced to preparedness all over which the private sector can prepare, compete and innovate. Here, all can understand classes from the Trump administration’s Procedure Warp Speed to the Biden administration’s subsequent vaccine and booster rollouts.  

In the long run although sources can come from Washington, we have to remember that care will be offered by state and area authorities and medical doctors, nurses, and EMTs on the pandemic entrance line. The federal federal government with its scale and resourcing is the metaphorical 800-pound gorilla in the room — it can do matters providers and even state and nearby governments can not.  

Nonetheless, it lacks the agility, adaptability and neighborhood/issue make any difference knowledge that the non-public sector, states and localities have. By investing in pandemic preparedness at this amount we can cut down the stress on the federal governing administration, and empower these at the issue of treatment. This usually means encouraging stockpiling at a area degree and augmenting local health care methods and networks. Below the federal authorities can use its dimensions and scale to get improved charges from private sector corporations, give direction for state and neighborhood communities and present a coordinating functionality in the occasion of a crisis.  

When we might experience extensive removed from COVID-19 the virus, its effects and its legacies are incredibly substantially with us. Placing the acrimonious politics to the aspect, we are even now registering bacterial infections, albeit at considerably-lowered rates and with much a lot less virulence and lethality. 

Now is not the time to come to be idle or complacent basically mainly because the immediacy of the danger has ebbed. Instead, it is the time to mirror on what worked and what didn’t, to double down on required reforms and prepare for the next sickness.

Glenn Nye is the president and CEO of the Middle for the Examine of the Presidency & Congress (CSPC). Dan Mahaffee is the senior vice president & director of Plan at the Centre for the Examine of the Presidency & Congress, exactly where he sales opportunities its Geotech Program.

CT legislators weigh allowing trade groups to offer health insurance

CT legislators weigh allowing trade groups to offer health insurance

Connecticut’s little companies and nonprofit corporations could see decreased health insurance plan costs less than a proposed monthly bill that would make it possible for trade associations to provide substantial group health plans to their customers. 

But affected person advocates say they’re anxious about language in the legislation, Residence Bill 6710, that could allow programs to demand increased rates to corporations employing individuals who get ill or wounded.

USPS health insurance marketplace launch gives OPM plenty to do in a busy 2023

USPS health insurance marketplace launch gives OPM plenty to do in a busy 2023

A significant Postal Support reform monthly bill signed into law final year is relocating postal workforce and retirees into a unique overall health coverage marketplace from the relaxation of the federal workforce.

The Postal Services Reform Act requires the Business of Personnel Administration to generate a individual Postal Provider Wellbeing Benefits plan (PSHB) in the Federal Worker Wellness Positive aspects (FEHB) system, starting off in January 2025.

The Postal Assistance Overall health Added benefits plan will give health coverage ideas to…

Examine Extra

A important Postal Support reform invoice signed into regulation last year is going postal workers and retirees into a various health and fitness insurance policy marketplace from the rest of the federal workforce.

The Postal Services Reform Act involves the Office of Personnel Administration to create a independent Postal Service Wellness Benefits method (PSHB) within just the Federal Employee Health Rewards (FEHB) application, commencing in January 2025.

The Postal Services Wellbeing Benefits program will offer overall health coverage options to eligible USPS workforce, annuitants and their qualified spouse and children customers. But the legislation specifies needs for postal-only wellness ideas that never utilize to ideas provided below FEHB.

OPM, meanwhile, faces a restricted timeline to build a parallel health rewards marketplace and on-line infrastructure for postal staff members and retirees ahead of an open up enrollment period in late 2024.

OPM Main Information Officer Guy Cavallo reported developing the PSHB is a “major initiative for us at OPM,” but additional that the agency is also managing many other big IT modernization projects this 12 months.

Cavallo, speaking on Feb. 8 at ATARC’s IT modernization summit, claimed Congress gave OPM a “very quick timeline” to produce the new PSHB program, presented the technical specs in the postal reform laws.

“They did not request us for our opinion on how extended would it acquire to do this, but I have that deadline,” Cavallo explained.

The postal-only well being insurance policies marketplace will come with its personal exceptional technical specs that do not implement to federal personnel underneath FEHB. The Postal Procedure Reform Act needs all future postal retirees to enroll in Medicare Portion B, in an work to help you save USPS tens of billions of pounds around the coming decades.

“So [they’re] fully distinctive requirements than the present Federal Staff Health Advantages program. That means our technique is going to have to double-examine and make positive that they enrolled in Medicare and that they are suitable,” Cavallo claimed.

The legislation expects OPM to generate and administer a parallel wellbeing insurance coverage marketplace for postal staff members and retirees, compared to what’s offered on the FEHB.

But the requirement for almost all upcoming postal retirees to enroll in Medicare needs OPM to construct particular one of a kind features into the PSHB procedure that aren’t constructed into its infrastructure for FEHB.

“We unquestionably have to have enrollment offered, we have to have an eligibility check out available. We have to be able to gather dollars from the Postal Assistance to shell out for the plans that the personnel have picked [and] we have to distribute that cash to every respective company,” Cavallo claimed.

Mainly because upcoming postal retirees should enroll in Medicare Part B, Cavallo mentioned overall health program carriers have to offer diverse designs than what they now supply beneath the FEHB.

The postal reform laws needs OPM, to the greatest extent probable, to guarantee the PSHB consists of each and every FEHB prepare that experienced at least 1,500 USPS staff members or retirees enrolled, as of January 2023.

“Because it is a lesser market place section, it’ll be scaled-down programs than the recent 160-170 plans that are readily available in FEHB,” Cavallo reported about the PSHB.

The PSHB, according to a February 2022 Congressional Investigate Report, would also incorporate strategies available by other non-FEHB insurers, as deemed proper by OPM.

John Hatton, personnel vice president for coverage and plans at the Nationwide Lively and Retired Federal Workers Association (NARFE), stated OPM must be capable to launch the PSHB “without significant modifications in coverage.”

“Some of individuals smaller sized designs, they could nevertheless be eligible to supply prepare possibilities in the postal software, but it’s probable they may well not,” Hatton said. “We undoubtedly want OPM to make all attempts to not just [get] these designs at that 1,500 threshold, but to involve as many prepare selections that are at this time in FEHB, in the postal system, to avoid reduction of existing insurance policies coverage for enrollees. That does not signify individuals are going to eliminate insurance coverage, they just really do not have to select a different plan.”

The Postal Assistance Reform Act is anticipated to help you save USPS about $22.6 billion above the subsequent decade by an elevated enrollment of USPS personnel and retirees in Medicare. Up coming to the rest of the federal government, USPS is the most significant contributor to the Medicare rely on fund in the state.

OPM final yr issued some steerage to postal staff members and retirees about the PSHB answering frequently requested questions about the new well being care system.

Current USPS staff and retirees will continue being in the FEHB for the rest of 2023 and 2024, but will no lengthier be capable to stay in an FEHB plan, powerful Jan. 1, 2025. Their present-day FEHB enrollment will carry on unless of course they make any changes prior to January 2025.

During Open Time in 2024, eligible folks ought to enroll in a PSHB program,  in get to receive wellness insurance policy primarily based on their active work with or retirement from USPS.

Below the PSHB, USPS workers and retirees would be equipped to enroll in self-only, self-plus-a person, or family members protection.

If a USPS personnel or retiree was enrolled in FEHB in 2024 and did not pick a PSHB program in 2025, OPM will instantly enroll them in a approach provided by the individual’s FEHB insurance company. If such a prepare is not accessible, OPM will enroll them in the cheapest-charge, non-large deductible, nationwide PSHB system that does not cost a membership rate.

Enrollment in a PSHB program will not disrupt enrollment in other coverage and added benefits programs, together with the Federal Personnel Dental and Eyesight Insurance policies Application (FEDVIP), the Federal Flexible Spending Account Plan (FSAFEDS), the Federal Employees’ Team Daily life Insurance (FEGLI), or the Federal Extended Term Care Insurance policies Plan (FLTCIP)

USPS spokeswoman Darlene Casey informed Federal Information Network that “OPM and the Postal Services will supply updates leading up to the 2024 PSHB open time to enable make certain a clean changeover for all eligible staff and annuitants.”

Insurers with strategies in PSHB and FEHB will be demanded in 2025 to be certain that their PSHB and FEHB designs have equal advantages and charge-sharing necessities, with specific exceptions.

PSHB rates will be determined individually from FEHB rates. That implies PSHB insurers will establish premiums based mostly on the amount of money of wellness treatment anticipated to be made use of by USPS personnel, retirees, and their dependents.

The USPS contribution toward annuitant rates would be calculated employing the exact same statutory method currently used underneath FEHB, but would be based only on PSHB prepare rates.

Present postal retirees, or USPS workforce 64 or more mature at the get started of the program, will not need to enroll in Portion B as portion of the switchover to the PSHB.

These USPS personnel and employees, having said that, will be suitable to voluntarily enroll in Medicare Section B as portion of a unique enrollment interval, without the need of becoming subject to late enrollment charges. That particular enrollment would get started in April 2024 and final for six months.

Hatton said NARFE encourages OPM to develop the PSHB with “as minor disruption as feasible,” both in phrases of loss of designs for postal staff and retirees, as nicely as in phrases of important changes to coverage for them.

“The lack of disruption and possessing clarity, I assume, are form of the most important problems OPM faces of implementation of this,” Hatton explained. “FEHB provides seriously high quality wellness coverage protection for federal workers and retirees, like postal staff and retirees, and producing positive they manage that by way of this changeover to this new method will be truly must be their leading precedence.”

OPM is setting up the PSHB on a cloud-dependent system, and options to use the task as a template for ultimately bringing the FEHB on to the cloud as effectively.

“My mandate was, ‘This procedure is not going to be on-premise, it is likely to be a cloud answer.’ The latest FEHB process is on-premise,” Cavallo reported. “Once we’re performed with this, then we’ll redo the Federal Health and fitness and Added benefits plan, leveraging in all probability the same system — possibly not the exact same vendor, but at the very least a cloud-centered system,” Cavallo claimed.

OPM, nevertheless, is juggling the creation of the PSHB marketplace as one of various prime IT modernization projects this year.

The company also acquired funding from the Technology Modernization Fund to modernize its general public-dealing with web site and speed up its adoption of a zero-have confidence in cybersecurity architecture.

Meanwhile, Cavallo stated OPM will have to also occur up with workarounds for a mainframe that is “getting around its close of life.”

“With the thousand systems on it, my drive would be to rewrite all of these, make them user-centric and cloud-based. I really do not have ample time,” Cavallo mentioned.

As a stopgap alternative, Cavallo explained OPM is functioning a examine on relocating the mainframe to the cloud in an “emulation manner, so that we really do not have to invest $14, $15, $16 million on components that, as soon as I can get out of that, I’m going to be turning that hardware off.”

Cavallo explained his crew holds a month-to-month task evaluate that typically lasts about 6 hours, since OPM averages close to ongoing 100 projects a thirty day period.

“Obviously, out of those people initiatives are some that are additional important than the other individuals. But it also doesn’t signify that we cannot be doing things in parallel,” Cavallo said. “The federal federal government requires to regularly modernize, even if I acquired all that completed, my operate is not performed. Simply because tomorrow, I need to modernize what we just applied and maintain going.”


China’s health insurance reform won’t cut benefits, unrelated to COVID: experts

China’s health insurance reform won’t cut benefits, unrelated to COVID: experts
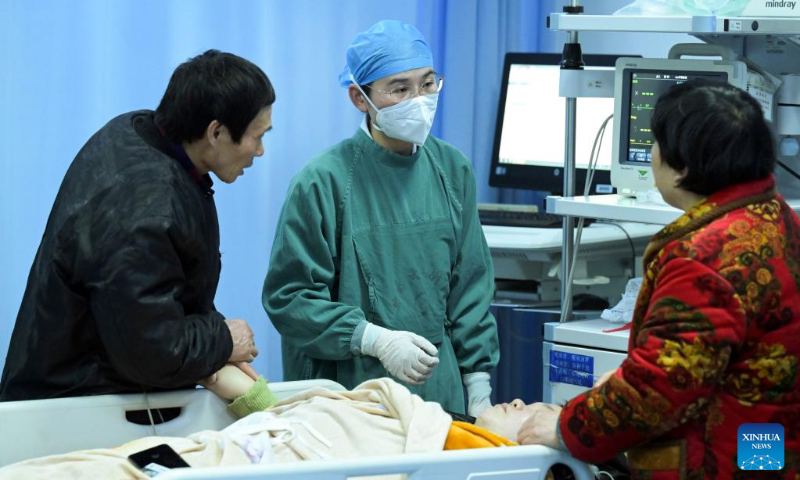
A medical worker talks with the relatives of a patient at the emergency department of the Second Affiliated Hospital of Anhui Medical University in Hefei, east China's Anhui Province, Jan. 21, 2023. Medical staff stick to their posts during the Spring Festival holiday. (Xinhua/Zhou Mu)

A professional medical employee talks with the kinfolk of a individual at the emergency section of the Second Affiliated Hospital of Anhui Clinical College in Hefei, east China’s Anhui Province, Jan. 21, 2023. Health-related employees adhere to their posts throughout the Spring Festival holiday getaway. (Xinhua/Zhou Mu)

A amount of Chinese localities, which include Central China’s Hubei, Southwest China’s Sichuan and Northeast China’s Heilongjiang, are employing a reform of wellness insurance policies for urban personnel and retirees, drawing widespread interest.

Industry observers said the reform, which lessens the volume deposited every month into private accounts, will not mean the reduction or reduction of well being insurance plan gains, nor is it a transfer to address COVID-19-connected expenses, as some Western media asserted.

The health insurance policy reform is a decision that has been created after decades of dialogue, scheduling and prudent thing to consider and sites Chinese family members in a greater posture to cope with medical hazards, and elderly individuals who are more vulnerable to health issues and incur better health care expenditures will benefit the most from the reform, observers mentioned. 

Wang Chaoqun, affiliate professor from Section of Labor and Social Stability at Central China Ordinary College, instructed the International Situations on Sunday that under the new plan, the reform can reimburse outpatient bills and alleviate the economic burdens of the insured, primarily elderly persons or people who often take a look at medical practitioners and find it is not enough to pay back for their fees. 

Formerly, the funds inside of particular accounts was significantly from sufficient in covering health-related expenditures in hospitals and pharmacies. Data confirmed that in a metropolis where by about 5 million people had joined the health care coverage system, much less than 5 percent of personal accounts had balances of extra than 10,000 yuan ($1456), and less than 1 {08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} experienced balances of more than 20,000 yuan, Wang pointed out. 

The threshold for the reimbursement percentage of outpatient health care expenses is 50 p.c, and in some towns these as Xiamen, a city in East China’s Fujian Province, the stage can reach as large as 98 {08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f}, according to Wang. 

For people who rarely see medical professionals and have tens of countless numbers of yuan sleeping in their accounts, the reform will really feel like a decline in the shorter phrase, but when they get more mature or if they come to be ill and want to see doctors commonly, they will eventually find that they profit from the reform, Wang reported. 

China’s wellbeing insurance policy process for urban staff and retirees is made up of two elements: necessary private accounts with contributions from both equally staff members and their employers that largely pay out for regular outpatient companies and a pooled fund contributed by businesses that is utilized to reimburse hospitalization charges, outpatient costs for severe diseases, and bills for some continual health conditions, according to the Xinhua News Company.

After the reform, revenue deposited by businesses into employees’ personalized accounts will be instantly paid out to the pooled fund in buy to guidance the reimbursement of regular outpatient clinical expenses. The reform was officially rolled out by the Condition Council in April 2021.

Some Western media have intentionally connected the reform of the health insurance to COVID-19 and asserted that the reform is attempting to allocate income from private accounts to make up the deficit of the health-related insurance coverage fund.

Their statements are designed only to smear China and absence basis, gurus claimed. The pooled fund has built ends fulfill in excess of the years, Jin Weigang, a professor at Zhejiang College, informed the World wide Occasions.

The overall income of China’s standard healthcare insurance policies resources in 2021 reached 2.8 trillion yuan (close to $439.7 billion) and the expenditure was 2.4 trillion yuan, according to the National Healthcare Security Administration (NHSA).

The reform is a selection that was manufactured soon after years of dialogue and in 2010, the Social Protection Law laid a lawful ground for the wellness reform, Wang famous, refuting any website link among COVID-19 and the reform.

Throughout the COVID-19 epidemic, expenses for vaccines and nucleic acid tests had been financed by the state, and some COVID-19 treatment options and medicine ended up lined by the health and fitness insurance coverage fund because it fit the reimbursement policy, Wang pointed out. 

As opposed with other nations around the world, the gains of China’s wellness system are noticeable. China has crafted a nationwide standard clinical insurance policies procedure covering in excess of 1.36 billion people, accounting for over 95 {08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} of the total populace. It is a mission hardly imagined for a establishing place.
  
But in the US, just before Obamacare, as a great deal as about 30 or 40 million People in america were uninsured and various reports have demonstrated that the very first lead to for people to go bankrupt in the US is the excessive higher cost of professional medical treatment, observers famous. 

China’s elderly protest health insurance cuts in Wuhan, Dalian

China’s elderly protest health insurance cuts in Wuhan, Dalian

Remark

A week of protests by Chinese pensioners over well being insurance policy improvements that decrease payouts for drugs and outpatient treatment has underscored stress on the Chinese Communist Get together to produce enhanced social care for a swiftly growing older population, even after regional govt coffers ended up seriously depleted by big “zero covid” expenditures.

On a drizzly afternoon past week, hundreds of aged gathered outside the house the metropolis hall in Wuhan, in central China, to oppose adjustments to condition well being insurance policies, such as reducing every month promises for medicine to 1-third of the past total.

Huddled beneath umbrellas and watched by law enforcement in vivid blue raincoats, the tranquil crowd sang revolutionary anthem “The Internationale” and chanted slogans calling for an explanation, in accordance to films of the scene shared commonly on the internet. If no resolution was reached, protesters reported, then they would phase a 2nd mass demonstration a week afterwards.

As promised, they filled central Zhongshan Park and close by streets Wednesday, with a second group collecting a couple of blocks away by the Wuhan Union Clinic.

This time, the authorities reacted much more forcefully. In an obvious endeavor to suppress attendance, the city’s metro cars and trucks did not prevent at the nearest station. Online video confirmed shoving matches as law enforcement tried out to comprise the protests. Some attempted to climb obstacles to escape the melee but ended up pulled back again by uniformed officers.

At the exact time as the standoff escalated in Wuhan, a further demonstration was beginning in Dalian, a city of 7 million on China’s northeast coastline, where hundreds of elderly wrapped up in puffy winter jackets descended on People’s Square to protest the exact same adjustments.

The unfold of discontent more than changes to social care will come only 3 months soon after Chinese chief Xi Jinping confronted mass social unrest above the excesses of his signature zero-covid coverage that disrupted day-to-day lifetime and hammered corporations. Soon afterward, the celebration abruptly reversed course. Infections soared, leaving hospitals and crematoriums overwhelmed.

Contrary to the unusually widespread and politically billed protests in November, one challenge protests like all those that took area in Wuhan and Dalian this week are popular in China, even under the security-obsessed Xi. Changes to pensions, education, housing and other foundational social guidelines often attract responses as folks petition to protect their legal rights.

Tracked, detained, vilified: How China throttled anti-covid protests

But these incidents put tension on Communist Social gathering claims that items can even now get improved for everyday persons in China as the nation confronts a new financial truth. The many years of breakneck advancement are around, but Xi has justified his norm-defying 3rd expression in portion by pledging a to return to the party’s egalitarian origins to development a central coverage agenda of “common prosperity” for the masses.

This sort of ambitious adjustments are not cheap or uncomplicated, and Xi has to provide them all through a time of strengthening financial head winds, together with a having difficulties home industry, weak usage and a shrinking populace.

What’s more, mass tests, quarantines and lockdowns have left already money-strapped nearby governments looking for methods to decrease prices. When changes to health-related insurance plan have been a long time in coming, retirees complain that they were being not consulted about the changes or presented assistance to modify to the new technique.

Declared in 2020, the adjustments goal to simplicity force on point out insurance cash that some specialists anxiety could operate out within just a ten years as the populace ages. The concept was to concentrate on important care by expanding funds in a centralized account employed for main inpatient treatment though lessening individuals obtainable in a private account used for outpatient services and medicines. While the revisions are a nationwide effort, the particular solution is decided locally.

Debates more than how to deal with condition wellness insurance policies resources are very likely to raise as the inhabitants ages, reported Aidan Chau, a researcher at Hong Kong-based mostly nongovernmental organization China Labor Bulletin. Even soon after the condition justified adjustments by indicating that the income need to be still left for people today who are most in need to have, staff in destinations like Wuhan who have fairly substantial cash in their unique accounts “think that it’s a slash in their gains,” he explained.

In Wuhan and Dalian, a lot of raised worries on the internet about currently being unable to claim as much for simple medications needed to avert onset of more severe signs.

“I can tell you with complete certainty that every single one retiree in Wuhan has grievances,” 1 resident advised a Wuhan governing administration criticism hotline in accordance to a recording that was shared extensively on the net. “Health insurance coverage need to get better with changes, but to do it this way signifies we will not be able to get remedy,” the caller said.

What you want to know about China’s covid protests

Confusion around no matter if the alterations disproportionately affect sure groups have fueled anger just after reports circulated on the internet that civil servants would be excluded from the decreased payouts. A web site affiliated with point out-operate Henan Day by day went as considerably as contacting Wuhan’s restructuring “radical” in its increasing of needs for statements and cancellation of payouts for gig workers.

Condition-operate China Nationwide Health Insurance Magazine denied the costs and stated the protesters experienced been “brainwashed” by rumors, declaring that “when you fully grasp the content there will be no question that older persons are the most important beneficiaries.”

As the metropolis where coronavirus was very first uncovered, Wuhan’s lockdown was amid the longest and most chaotic in China. During the original outbreak, authorities pledged to cover the charges of all covid-related treatment, with substantially of that price becoming borne at the community level. And that bill continued to develop as the regime of ad hoc restrictions continued into late 2022, extended past when most of the rest of the world experienced learned to reside with the virus.

The city expended $1.3 billion on covid and other related community health and fitness charges in fiscal calendar year 2022, in accordance to a monetary bureau spending budget report submitted to the neighborhood legislature in January 2023. Dalian used $408 million to fight coronavirus in 2022.

Lyric Li in Seoul, Theodora Yu in Hong Kong and Vic Chiang in Taipei contributed to this report.