Millions in the U.S. May Lose Medicaid Coverage. Here’s How to Prepare.

Millions in the U.S. May Lose Medicaid Coverage. Here’s How to Prepare.

All through the pandemic, millions of People on Medicaid have been shielded from getting rid of overall health care protection. Medicaid gives well being coverage for very low-earnings Individuals for the past 3 decades, states suspended their normal method of redetermining no matter if an individual remained suitable for coverage.

States need to now reverify that each individual Medicaid receiver however qualifies for the software within just the subsequent 14 months.

Quite a few men and women will carry on the exact Medicaid coverage they’ve had for several years, but hundreds of thousands could shed access to their latest coverage — both for the reason that they do not qualify for Medicaid any more, or even if they do go on to qualify, since the administrative hurdles to renew their protection are so high. In certain, people with disabilities, people who are not indigenous English speakers and men and women who improved addresses in the course of the pandemic may perhaps wrestle to wade by means of the purple tape, stated Lindsay Allen, a wellness economist and Medicaid coverage researcher at Northwestern Medication.

States can start out the process of disenrolling persons who are not suitable on April 1, and they have 14 months from that day to entire the redetermination procedure, with persons dropping coverage intermittently throughout. Every point out will have a a bit unique approach, and most will consider a whole year to operate their way via each individual Medicaid enrollee.

“There’s 92 million people in our country that need to have to fill out paperwork all at after, in a pretty confined total of time,” said Dr. Jose Francisco Figueroa, an assistant professor of wellbeing plan and administration at the Harvard T.H. Chan Faculty of Community Overall health.

Some folks will get kicked off Medicaid simply because they make considerably a lot more money than they beforehand did. Some overall health policy gurus are anxious about these who keep on being eligible but really do not have the time or sources to total what can be a cumbersome renewal procedure.

“We’re nervous that a lot of persons, when they go check out to agenda an appointment with their health practitioner, somebody’s likely to notify them, ‘Oh, you really don’t have coverage any more,’” Dr. Figueroa explained.

If you have moved, your latest state’s Medicaid system may perhaps have a harder time reaching you.

“We know whenever these kinds of times transpire, it’s individuals of color, it’s young children, it’s individuals that really do not converse English that are usually hit the most difficult,” said Natalie Davis, a founder and the chief govt of United States of Treatment, a nonpartisan advocacy corporation that supports expanding obtain to health and fitness treatment.

It’s vital to make absolutely sure your contact info is up-to-day with your point out Medicaid business. In several states, you can produce an account on your state Medicaid internet site, wherever you can confirm that your info is correct and update your communication choices. And you can normally locate the mobile phone number of your state’s Medicaid place of work to call and validate, while get in touch with facilities may perhaps be specially bogged down throughout this period of time.

View for interaction from your state Medicaid place of work — notices in the mail, telephone calls, email messages. Some states have by now begun contacting people today to tell them about the renewal process.

Although all states will have to get started calling enrollees by April, most folks will not acquire this renewal detect for months, said Jennifer Tolbert, an affiliate director of the System on Medicaid and the Uninsured at the Kaiser Household Basis. “I do be concerned that there’s all this urgency close to April 1 and when nothing at all significant happens in April that everybody just breathes this massive sigh of relief and claims, ‘Oh, I’m high-quality, I really do not have to get worried about this.’ But which is not going to be the situation.”

Various states may perhaps demand unique documentation, but in common, they will want to confirm your profits, address and regardless of whether you have experienced a change in the number of dependents, explained Ms. Davis. You may possibly acquire a observe asking to ensure or update your economic or other facts persons usually are specified 30 times to reply, Ms. Tolbert mentioned.

“Everyone who’s on Medicaid now: Assume to fill out paperwork,” Dr. Figueroa mentioned.

If you’re notified that your Medicaid protection has been terminated but you consider you go on to qualify, the very first detail you ought to do is obtain out if you missing protection inappropriately, Ms. Tolbert mentioned. Get hold of your condition Medicaid workplace — while keep in intellect that connect with facilities are probable be swarmed, she recommended.

“Don’t give up if you just cannot get by way of via the telephone,” she stated. “Stick with it.” You can request what is recognised as a honest listening to course of action, to enchantment the state’s determination to terminate your Medicaid rewards.

You can find a listing of businesses that can enable you navigate Medicaid renewal at Localhelp.healthcare.gov.

If you are no lengthier qualified for Medicaid, your ideal wager is to request out subsidized insurance policies by likely to the on-line Cost-effective Treatment Act marketplaces either operated by your point out or readily available at Healthcare.gov. The American Rescue Strategy expanded insurance policy subsidies, so people who lose obtain to Medicaid could even now be in a position to locate an cost-effective program, Ms. Tolbert reported. But some people in the 10 states that have not beforehand expanded Medicaid will be still left in a coverage hole, she stated, not qualified for backed insurance policies but also unable to qualify for Medicaid.

If you are used, you may be equipped to get protection from your employer. Access out to your H.R. division in just 60 days of losing protection — the sooner, the improved — to check with about coverage. If you’re married, your husband or wife could want to question their employer about probable protection possibilities that can implement to you if you’re an adult less than the age of 26, you could also be ready to change to your parents’ insurance policies.

And if you’re a dad or mum, just simply because you have lost coverage doesn’t normally imply your child will. Any notification that you’re no longer qualified for Medicaid must clarify if your little one retains coverage, Ms. Tolbert mentioned — but if you’re unsure of your child’s standing, get in touch with your condition Medicaid business.

It is the compounding excess weight of these intricacies — uncertainty in excess of which program covers which household member, confusion about what information a person wants to qualify for Medicaid — that coverage professionals get worried will additional burden Medicaid recipients. The additional pressure of redetermination adds a “mental tax,” Ms. Davis explained.

But as the redetermination process kicks off, monitoring down make contact with details for condition agencies you can flip to in advance and viewing for vital communications can enable you put together. “If you’re proactive, you can lower the likelihood of a hole in your protection,” Dr. Allen mentioned.

300,000 Oregonians at risk of losing state health insurance. Here’s why.

300,000 Oregonians at risk of losing state health insurance. Here’s why.

An estimated 300,000 Oregonians could drop condition health and fitness insurance policy in the future 16 months for the reason that they no for a longer period qualify for point out protection built far more commonly accessible during the COVID-19 pandemic.

All close to 1.5 million men and women getting protection via the condition will shortly require to be fiscally qualified for the plan to maintain their point out health and fitness insurance plan, subsequent a three-12 months federal reprieve from standard specifications because of to the pandemic.

That reprieve is quickly coming to an end, offering state officers just around a calendar year to make positive absolutely everyone who qualifies for protection retains it.

“Our actual purpose is to make absolutely sure that we preserve all the advantages that we can,” interim Oregon Wellbeing Authority director James Schroeder stated in a presentation to lawmakers Tuesday. “But at the conclusion of the working day, people are both heading to be suitable or not.”

Below federal rules place in place shortly immediately after the pandemic started off, Oregonians did not have to confirm economical hardship or get the job done position in purchase to qualify for Medicaid coverage, which in Oregon is termed the Oregon Wellness Strategy. Coverage expanded considerably in the final a few a long time, from about 1,080,000 Oregonians right before the pandemic to about 1,470,000 right now, according to state details.

But on April 1, Oregon will begin a 14-thirty day period process to validate that people do not make way too much cash to qualify for the lower-profits wellbeing coverage method and fulfill other prerequisites. The condition will comply with up with individuals who no for a longer period qualify to assist them transition to protection as a result of the wellness insurance plan marketplace, officials mentioned.

The Oregon Department of Human Services, which is dependable for examining eligibility for its own applications and for the health authority, called the quantity of function in advance “historic.”

“We are serving the best caseload we’ve at any time experienced in the heritage of our point out,” mentioned Nate Singer, who oversees the eligibility system. “There are additional people acquiring benefits in the point out of Oregon at this time than we’ve at any time served in advance of on these applications.”

Well being officers explained they will now require to get to and listen to back from all those enrolled in the Oregon Overall health System and talk to for proof they are eligible, as was the exercise as soon as a yr prior to the pandemic.

Except the point out previously has proof by way of other signifies, qualified people who are unsuccessful to respond could shed protection.

“That is some thing that we, I consider, all locate unconscionable, and we want to stop,” interim Medicaid director Dana Hittle claimed Tuesday.

Medicaid traditionally serves persons who could be difficult to achieve possibly simply because of linguistic or cultural obstacles or simply because they do not have secure housing, officials stated, earning it particularly crucial to consider further attempts to speak to them.

To that stop, Schroeder and Hittle implored lawmakers to convey to their constituents how crucial it is for them to be certain the state’s call facts is up to date. The wellness authority also is now able to use the addresses clients give their wellbeing treatment providers, which the agency explained it could not formerly do.

The plan, for now, is to stagger the Medicaid renewal system over 14 months, setting up with people today who the point out expects will be simple to re-enroll. A man or woman who gets a notice from the state will have 90 times to respond, up from 30 times prior to the pandemic. If they really don’t, the point out will consider to get hold of them again, providing the person 60 a lot more days before they drop coverage.

“Despite all of the organizing and the do the job that we’re performing to approach for all of the eventual troubles that could happen, it is not going to be a pretty, sleek approach,” Hittle stated. “It is an extremely hard piece of perform.”

In addition to the expected fall in point out-funded health and fitness treatment protection, about 426,000 Oregonians next month will reduce supplemental foods gains expanded all through the pandemic due to the fact the federal funding is ending. The software, readily available because April 2020, came on top of normal Supplemental Nourishment Help Application added benefits, formerly known as foods stamps.

The system allocated about $70 million in added money very last thirty day period, or an common of $167 per eligible human being.

— Fedor Zarkhin

It’s open-enrollment season: Here’s what to know if you’re considering a high-deductible health plan

It’s open-enrollment season: Here’s what to know if you’re considering a high-deductible health plan

By Leslie Albrecht

When does a large-deductible overall health strategy make feeling? Here is who can profit the most from an HDHP.

Hi there and welcome to Financial Deal with-off, a MarketWatch column in which we help you weigh economical conclusions. Our columnist will give her verdict. Convey to us no matter if you believe she’s ideal in the comments. And please share your recommendations for foreseeable future Economical Facial area-off columns by emailing our columnist at lalbrecht@marketwatch.com.

The face-off

It is really the time of year to signal up for a new health insurance prepare, either through an employer or via the government’s Health and fitness Insurance coverage Market.

The choice might feel particularly fraught this 12 months. Significant inflation, layoffs and a possible recession are weighing on people’s minds and funds. Americans have been tightening their budgets and may possibly be wanting for means to conserve money on their wellness-insurance coverage prices. 1 way to do that, at the very least in terms of upfront fees, could be to signal up for a substantial-deductible well being plan. These ideas usually have decrease regular monthly charges (premiums), but they have better deductibles, or, the volume of revenue that you have to spend out of your own pocket just before the insurance kicks in to include healthcare expenses.

So is this the 12 months to try to save some money by signing up for a large-deductible well being plan?

Why it issues

It’s no secret that healthcare is high-priced in the U.S., but the language of wellness coverage often obscures that actuality with euphemisms these kinds of as “charge-sharing,” “coinsurance,” “copay” and “deductible.” This is a swift translation: if you see a person of people phrases, just mentally exchange it with a dollar sign, simply because it means you will be paying out money.

Deciding upon a health care plan is significant. Healthcare charges can strain a household’s funds, and health care personal debt is very common. Far more than 50 {08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} (57{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f}) of People have incurred financial debt brought on by a health care or dental expenditure in the previous 5 yrs, according to a nationally agent study produced in June by KFF, an independent nonprofit that researches health care troubles.

1 of the survey’s much more troubling results was that even folks who have health and fitness insurance plan drop into credit card debt, with far more than four in 10 insured adults reporting that they currently had health-relevant credit card debt.

In other phrases, the decision about which wellness-insurance coverage prepare to pick out can have significantly-achieving unintended implications.

How much can you assume to pay out for health insurance policy? If you get yours by way of your occupation, it is dependent on various things including the dimensions of your corporation and the age of its workforce. On common, staff with employer-centered health and fitness insurance coverage compensated $6,106 per calendar year toward family members coverage and $1,327 for personal coverage, according to KFF. Men and women at lesser corporations usually have larger premiums and more substantial deductibles.

The federal government defines a high-deductible wellness system as just one with a deductible of at least $1,400 for an person and $2,800 for a family members.

Higher-deductible overall health programs (HDHPs) often — but not generally — come with a health price savings account (HSA) in which individuals can shop funds tax-free of charge to pay for health care expenditures.

HDHPs have reduced rates, but are they additional affordable in the long run than traditional health plans? ValuePenguin in contrast HDHPs vs. classic designs in three eventualities and discovered that the HDHP program holder would stop up spending additional general than the conventional system holder if they experienced healthcare expenditures of $5,000 or $10,000 in a 12 months.

On the other hand, the HDHP holder had lower all round prices than the traditional prepare holder if their healthcare bills have been $1,000. “But banking on these types of an outcome — and this kind of low have to have for clinical care — can be a gamble in an unpredictable earth,” ValuePenguin wrote.

The verdict

If you can spend the greater regular monthly expenditures, stay clear of a substantial-deductible well being program.

My reasons

“It is really incredibly difficult to accurately predict what your health-treatment wants are going to be for the coming calendar year. And for that motive, it’s a great plan to indicator up for the most in depth strategy alternative that you can afford to pay for,” mentioned Karen Pollitz, a senior fellow at KFF. Acquiring the cheapest possibility can open you up to the chance that one thing is going to take place — you will get hit by a automobile, uncover a lump — and then “you are going to locate out the tricky way how a great deal your system won’t include and what you are heading to owe out of pocket,” Pollitz stated.

As the KFF study located, health care financial debt is widespread even among the individuals with health and fitness insurance policies, she famous. “There are tons of reasons for that, but superior deductibles are a single culprit,” Pollitz explained.

That debt can have serious long-term outcomes, such as wrecking your credit score rating, or forcing you to reduce again on other residence costs like essentials like groceries, utilities and hire. You could even get into a condition where by medical practitioners refuse to handle you if you’re not paying your payments on time, leading you to delay desired overall health care. “Healthcare personal debt definitely can be the gift that keeps on providing,” Pollitz claimed, referencing the ongoing destructive impacts on people’s funds.

Is my verdict very best for you?

On the other hand, HDHPs with health and fitness financial savings accounts hooked up to them can make good monetary feeling for “one particular team,” Pollitz stated: individuals who are “wealthy ample to need a tax-desired discounts mechanism” and can manage to pay back whatsoever overall health expenditures could arise. “Associates in law firms usually indication up for them, but the associates and secretaries normally would favor not to,” she extra.

Wellbeing savings accounts (HSAs) are a excellent way to increase prosperity more than time, reported Eric Roberge, a certified financial planner and founder of Outside of Your Hammock, a Boston-based payment-only financial arranging agency. “You get to lead pre-tax dollars, and any expansion on the funds you invest in the HSA is tax-no cost as effectively,” he told MarketWatch. “If you withdraw funds and use it on competent clinical expenditures, that is also tax-totally free. It truly is the only account that presents this triple tax gain.” After age 65, you can use your HSA money for nearly anything, not just healthcare bills, but you will have to pay taxes on the withdrawals.

A higher-deductible health prepare with an HSA can do the job perfectly if you are younger, healthy and really don’t incur a great deal of professional medical expenditures. But if you use medical expert services commonly or have a lot of significant-price prescriptions, for instance, this may possibly not be the best option, since the cost of the higher-deductible wellness prepare may well not be truly worth the access to the HSA, Roberge noted. “For people who can regulate their health care bills devoid of difficulty though they’re earning an cash flow from their occupation and do not usually have a lot of medical expenditures each yr, opting for the HDHP can not only preserve you on premiums each 12 months, but it also provides you a opportunity to increase prosperity for the very long-term in a extremely tax-advantaged way via an HSA,” Roberge said.

Explain to us in the responses which possibility need to gain in this Economical Face-off. If you have thoughts for future Economical Experience-off columns, deliver me an email at lalbrecht@marketwatch.com.

-Leslie Albrecht


(End) Dow Jones Newswires

12-26-22 1203ET

Copyright (c) 2022 Dow Jones & Company, Inc.

Final Days to Use Your FSA Money: Here’s What You Could Get

Final Days to Use Your FSA Money: Here’s What You Could Get

This story is part of 12 Days of Tips, helping you make the most of your tech, home and health during the holiday season.

Your flexible spending account (FSA) provides a delicate balance of risk and reward. On the positive side, you get tax-free contributions toward expected health costs like over-the-counter medicine, screening tests and medical equipment. On the negative side, you usually have to spend your money every year or you lose it. (Don’t let your company take your money.)

CNET 12 Days of Tips logo

FSA funds can be used for medical treatments, insurance deductibles and copayments and for prescription medicine that isn’t covered by insurance, but a whole long list of items and health services can be FSA eligible, including several you may not have considered, like face masks, yoga classes or sunscreen. 

Read on to find all of the possible ways to spend your FSA money before the end of 2022. For more, read about the best life insurance companies or the best pet insurance.

What is a flexible spending account, or FSA?

Flexible spending accounts (also called flexible spending arrangements) are a type of “cafeteria plan” from employers that allow people to use tax-free contributions from their paychecks for specific expenses. There are several types of FSAs, but the most common are health FSAs, which participants can use to pay for medical and dental costs that aren’t covered by insurance.

With an FSA, you’ll decide how much you want to contribute at the beginning of the year, and your employer will deduct a portion of it from every paycheck.

The maximum amount an employee can contribute to an FSA is $2,850 for 2022 and $3,050 for 2023. Employers might provide additional funds to FSAs as a benefit, but those funds do not impact the employee contribution limit.

Traditionally, employees with FSAs will file claims with their employers to receive reimbursement for eligible expenses. Some companies now issue a debit card with FSAs so that plan participants can make purchases directly from their accounts.

Most FSAs follow a “use it or lose it” system where unused funds at the end of the year revert to your employer, with two possible exceptions. Changes to the laws on FSAs in 2021 allow companies the option of giving employees either up to a two-and-half-month grace period (that is, until March 15, 2023) to use FSA funds; or carrying over funds up to $610 into the following year. If you do carry over money from 2022 into 2023, that does not affect your yearly contribution limit of $3,050. 

Employers are not required to provide either FSA continuation option to their employees, however. Every company has its own FSA rules, so be sure to check with your FSA plan administrator or human resources department for the exact details of your plan.

What can I spend my FSA money on?

Along with medical treatment such as doctor and emergency room visits, insurance deductibles and copayments, and prescription medicine, there is a long list of approved products and services that are eligible for FSA coverage.

While some FSA items are automatically eligible for everyone, other products and services require a letter of medical necessity (LMN) from a licensed physician. The following list of FSA-eligible products is not completely exhaustive, but it covers all of the major categories of medical and dental care that can be paid for with FSA money:

Over-the-counter medicine: OTC medications were not FSA eligible until the passage of the Coronavirus Aid, Relief, and Economic Security Act in 2020. Now, cold, flu and allergy medications, pain relief like ibuprofen and acetaminophen, motion sickness pills, glucosamine sulfate for joint pain and other OTC medicine all qualify for FSA claims. First-aid kits and supplies like adhesive bandages and antibiotics are also eligible.

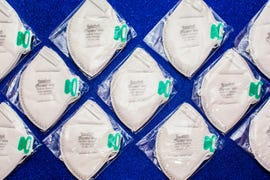
A photo of N95 face masks wrapped in plastic on a blue background

The IRS added COVID-19 protections like face masks to the FSA eligibility list in 2021.


Sarah Tew/CNET

COVID-19: COVID-related products such as face masks, at-home tests and hand sanitizer qualify for FSA reimbursement.

Dental procedures and products: Your dentures, implants, bridges and sealants are all covered by FSA, as are dental reconstruction and wisdom teeth removal. FSA funds can usually cover orthodontia, including Invisalign. Veneers require an LMN from a dentist.

Vision: Not only can you use your FSA funds for prescription eyeglasses and prescription sunglasses, you can also use them for non-prescription reading glasses or blue-blocker glasses. Similarly, contact lenses and supplies, including cleaning solution and lens cases, are eligible for FSA coverage, as are cataract and laser eye surgery.

Hearing: Your FSA money can be used for hearing aids, as well as batteries and maintenance for those aids. Telephones for the hearing impaired are also covered, as are products like ear cleaners and wax removers.

Breathing: Respiratory products such as nasal spray, inhalers and vaporizers are eligible for FSA coverage. With an LMN from a doctor, air conditioning, air filters and air purifiers can all be eligible for reimbursement.

Sleep: Along with OTC sleep medications, your FSA money can also be used for CPAP machines for sleep apnea and mouth guards to prevent teeth grinding. Prescription sleep medicine is also included. Items such as pillows with lumbar support or melatonin can be covered with an LMN from a doctor.

Preventive screenings: Take care of yourself with tests to evaluate your health that can be paid for with FSA money. Eligible screenings include DNA testing, heart scans, cancer screening, diabetes screening, HPV and HIV screening, breast cancer mammography screening and CT scans, as well as any blood tests that aren’t covered by insurance.

Pregnancy and sexual health: Most pregnancy related items and services are eligible for FSA funding, including pregnancy tests, prenatal vitamins, infertility treatments, intrauterine insemination and in vitro fertilization (IVF), as well as costs related to egg donors, surrogates, and egg and embryo storage. Men can use FSA funds on vasectomy reversal and Viagra.

Babies: FSA funds can cover many newborn-related expenses, including breast pumps, lactation consultants, breastfeeding classes, breast milk storage bags, diaper rash ointment, children’s sunscreen and baby breathing monitors. Infant formula can qualify, but only with an LMN from a doctor.

Contraception: FSA funds can help prevent unwanted pregnancies as well. Birth control pills, tubal ligation, vasectomies and condoms are all eligible. Levonorgestrel-based “morning-after pills” like Plan B One-Step or Take Action are eligible for FSA funding, as are all legal abortion procedures, including RU 486 pills (Mifepristone).

Menstruation: Pads, tampons, period underwear, pain relievers and other menstrual supplies all qualify as FSA expenses.

Medical equipment: Most products for measuring health are eligible for FSA money. Examples are thermometers, blood pressure monitors, blood sugar test kits and pulse oximeters.

Batteries: Along with the medical equipment itself, if you use batteries to power medical devices, they are FSA eligible.

Mental health: You can use FSA money for mental health treatments and services, including therapy and counseling in person or online. Visits to psychologists or psychiatrists are eligible, as are psychiatric care and prescription medicine. Unfortunately, marriage and couples counseling are not eligible for FSA reimbursement.

Addiction: FSAs can cover smoking cessation treatments and products to help stop smoking, like nicotine gum or patches. They can also cover donations to Alcoholics Anonymous meetings and the cost of transportation to attend, as well as other substance abuse programs and treatment for gambling addiction. An LMN is required to cover the cost of staying at a halfway house.

Weight loss: Weight-loss programs are eligible for FSA coverage, as are gastric bypass or lap-band surgeries. Prescription drugs for weight loss can also be covered by FSA money.

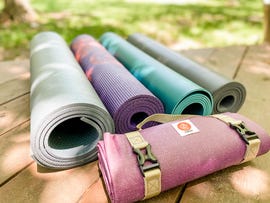
four yoga mats rolled up outside on a deck

Yoga mats and classes can be paid for with an FSA, but only with a letter from a doctor.


Amanda Capritto/CNET

Physical fitness: Most fitness expenses aren’t eligible for FSA coverage unless they are prescribed by a physician with an LMN. These expenses, if doctor recommended, can include personal trainers, gym memberships and yoga classes.

Athletic protection: If you’re looking to keep yourself safe and healthy during athletic activity, your FSA funds will cover many items, including athletic tape, braces and bandages, cups, face masks and mouth guards.

Muscle therapy: Most physical therapy is eligible for FSA funding, including massage devices at home. You can also use your FSA money for carpal tunnel supports, back braces or heating and cooling pads.

Foot care: Even though you can’t use FSA funds for athletic shoes (no matter how orthopedic) you can still use FSA money for healthy feet. Supports for high or low arches, foot care products and corn removers are some of the items eligible for FSA coverage.

Transportation: FSA money can be used to pay for travel expenses related to medical care or advice, including airplane tickets, gas for driving, mileage and maintenance costs, parking, bus or train fares and lodging.

Alternative medicine: A few nontraditional medical products and practices are eligible for FSA funding, including acupuncture, chiropractic services, homeopathy and holistic medicine.

Health-related home improvements: If you need to make changes to your living situation to account for an injury or medical situation, your FSA money should be eligible for most of it, including wheelchair ramps, grab bar installations, wider doorways, lowered kitchen cabinets or counters and home elevators, 

Mobility: For help getting around, FSA money can cover many products, including scooters, wheelchairs, crutches, canes and artificial limbs. Modifications to automobiles can also be eligible for FSA reimbursement with an LMN from a doctor.

Where can I buy products eligible for FSA spending?

You can purchase FSA-eligible products and services anywhere, as long as they qualify for reimbursement. Many major online retailers have created FSA-eligible stores that include all of the products that can be bought with FSA funds. 

Amazon, CVS, Target, Walgreens and Walmart all have their own FSA/HSA stores to make it easy to find qualifying medical and dental products.

Which expenses can’t be paid for with FSA money?

Despite the long list of potential uses for your FSA money, there are some medical and dental items that don’t qualify. Here is a list of products, services and expenses that are not eligible to be covered by FSAs:

  • Adoption expenses
  • Athletic shoes
  • Baby bottles
  • Bug repellant
  • Cannabidiol (CBD) products
  • Car seats
  • Cotton swabs
  • Dehumidifiers
  • Dental floss
  • Deodorants
  • Hair regrowth or hair removal products (including electrolysis)
  • Health or dental insurance premiums
  • Lactaid or other lactose-intolerance medication
  • Latex or nitrile gloves
  • Liposuction
  • Marriage counseling
  • Mattresses
  • Medical marijuana
  • Paternity testing
  • Protective goggles or safety glasses
  • Shampoo, soap, shaving cream or skin moisturizer
  • Smoke or carbon monoxide detectors
  • Summer or athletic camps
  • Tattoo removal
  • Teeth whitening or bleaching
  • Toothbrushes or toothpaste
  • UV protective gear
  • Veterinarian costs
  • Weight-loss supplements

For more health-related reading, learn how colder weather in winter can impact your breathing.

Holidays can cause huge stress. Here’s how to cope

Holidays can cause huge stress. Here’s how to cope

Those people holiday getaway movies that attribute family members collected by a hearth with a blanket of snow outdoors may possibly glance idyllic, but they have very little to do with reality and can even pose a hazard to your psychological wellness.

“Holiday motion pictures, performs and Television set are inclined to be idealistic. They portray perfect conditions that few people definitely have, and that can make them triggers for depression,” stated Debra Wentz, president of the New Jersey Psychological Health Institute.

They amplify what individuals feel is missing in their possess lives, Wentz explained. Visions of “utopia” and what perfect holiday seasons must be like get bolstered.

From the old movies to social media, we are set up for failure with unrealistic expectations, experts say.

Substantial charges:Inflation will generate up your property heating payments. Here is how NJ can get support