3 Medical Instruments Stocks to Buy Amid Improving Industry Trends

3 Medical Instruments Stocks to Buy Amid Improving Industry Trends

The Medical Instruments industry has witnessed a significant transformation in the nature of business lately, leading to increased investment in R&D for the development of cutting-edge technologies. The dynamic nature of the healthcare crisis over the past two and a half years has further altered the industry landscape, putting robotic and remote medical services in the limelight. Despite the reopening of the economy, deteriorating international trade, with global inflationary pressure leading to an extremely tough situation related to raw material and labor cost as well as freight charges, has put the industry in a tight spot again. Further, industry watchers are still unable to gauge the magnitude of economic revival due to the emergence of new COVID strains in selective parts of the world from time to time.

The just-reported fourth-quarter result of a number of medical instrument companies confirmed a gradual rebound in their base businesses through the latter half of 2022. However, the industry-wide trend of staffing shortages and supply chain-related hazards are denting growth. Meanwhile, industry players like Edwards Lifesciences EW, IDEXX Laboratories IDXX and Hologic, Inc. HOLX have adapted well to changing consumer preferences and are still witnessing an uptrend in their stock prices.

Industry Description

The Zacks Medical – Instruments industry is highly fragmented, with participants engaged in research and development (R&D) in therapeutic areas. This FDA-regulated industry comprises an endless number of products, starting from transcatheter valves to orthopedic products to imaging equipment and robotics. Prior to the pandemic, the Medical Instruments space was advancing well in terms of R&D. Among the recent path-breaking inventions, bone growth stimulators, 3D mapping of CT scans, wireless brain sensors and human-brain pacemakers are worth mentioning. During the COVID-hit years, many non-COVID and non-emergency-line innovations were stuck or delayed. However, with the severity of the pandemic easing, the industry players are again more focused on strengthening their pipeline.

3 Trends Shaping the Future of the Medical Instruments Industry

Business Trend Disruption: Considering the ongoing macro-economic situation, the IMF came up with its January 2023 World Economic Outlook Update. The update noted that global growth might slightly slow down from 3.4{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} in 2022, to 2.9{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} in 2023, then again rebound to 3.1{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} in 2024. IMF specifically addressed the ongoing tightening financial conditions in most regions, staffing shortages, Russia’s continued aggression, all of which have been weighing heavily on the medical instrument outlook despite the decline in COVID-19 severity. Per IMF, through 2023, inflation could remain stubbornly high, with continued labor market tightness and growing wage pressures requiring tighter monetary policies. On a brighter note, strengthening household balance sheets and wage growth are driving private demand. Overall, the Medical Instruments industry players are expected to collectively report a year-over-year decline in their revenues due to logistical challenges and increasing unit cost. This might get offset by an increase in essential and non-essential product demand by private households.

M&A Trend Continues: The medical instruments space has been benefiting from the ongoing merger and acquisition (M&A) trend. In fact, various reports suggest that M&A has been the key catalyst in the U.S. MedTech space of late. It is a known fact that smaller and mid-sized industry players attempt to compete with the big shots through consolidation. The big players attempt to enter new markets through a niche product. Among the significant deals of recent times, in December 2022, Johnson & Johnson completed the $16.6-billion mammoth acquisition of Abiomed. In February 2023, Abbott announced its plans to acquire Cardiovascular Systems, a medical device company with advanced atherectomy system used in treating peripheral and coronary artery disease. The same month, Globus Medical announced its plans to acquire the San-Diego based spine technology firm, NuVasive Inc., in an all-stock deal valued at around $3.1 billion.

Meanwhile, a MedTech Dive report of January 2023 revealed that MedTech players are expected to demonstrate a slow start to 2023 in terms on M&A. Yet, the experts say that despite higher interest rates and a volatile stock market, there are signs that strategic M&As are poised to rebound.

Digital Revolution: With an increase in the adoption of digital platforms within the medical device space, robotic surgeries, big-data analytics, bioprinting, 3D printing, electronic health records (EHR), predictive analytics, real-time alerting and revenue cycle management services are gaining prominence in the United States. A June 2019 Health care News report suggested that this market, valued at $123 billion in 2018, has been witnessing a CAGR of 25{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f}. Various other reports suggest that companies that adopted AI witnessed a 50{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} reduction in treatment costs. Telemedicine stocks received an impressive response when, in 2021, the Centers for Disease Control and Prevention asked healthcare service communities to broaden the use of telemedicine.

Zacks Industry Rank Indicates Good Prospects

The Zacks Medical Instruments industry’s Zacks Industry Rank, which is basically the average of the Zacks Rank of all the member stocks, indicates encouraging near-term prospects. The industry, housed within the broader Zacks Medical sector, currently carries a Zacks Industry Rank #85, which places it in the top 34{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} of more than 250 Zacks industries. Our research shows that the top 50{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} of the Zacks-ranked industries outperforms the bottom 50{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} by a factor of more than 2 to 1.

We will present a few stocks that have the potential to outperform the market based on a strong earnings outlook. But it’s worth taking a look at the industry’s shareholder returns and current valuation first.

Industry Underperforms S&P 500, Sector

The industry has underperformed the Zacks S&P 500 composite and its sector in the past year.

The industry has declined 9.5{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} compared with the S&P 500’s 6.9{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} fall in a year’s time. The broader sector has declined 9.3{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} in the said time frame.

One Year Price Performance

Industry’s Current Valuation

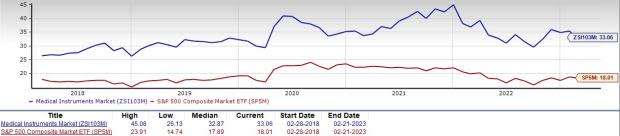
On the basis of the forward 12-month price-to-earnings (P/E), which is commonly used for valuing medical stocks, the industry is currently trading at 33.06X compared with the broader industry’s 22.40X and the S&P 500’s 18.01X.

Over the past five years, the industry has traded as high as 45.08X, as low as 26.13X and at the median of 32.87X, as the charts show below.

Price-to-Earnings Forward Twelve Months (F12M)
Price-to-Earnings Forward Twelve Months (F12M)

3 Stocks to Buy Right Now

Hologic: Headquartered in Bedford, MA, Hologic develops, manufactures, and supplies diagnostics, medical imaging systems and surgical products, which cater to the healthcare needs of women. Hologic has been making impressive progress in its Breast Health arm in recent times. The company is currently focusing on expanding its strategy to diversify business across the patient continuum of care. The company’s GYN Surgical business too has transformed to the most profitable division of Hologic on a percentage basis banking on new leadership, strong strategic execution of new commercial models and new product launches.
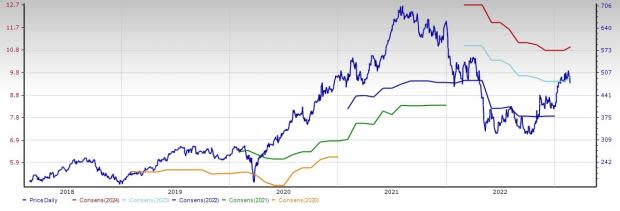
The consensus estimate for this Zacks Rank #1 (Strong Buy) company’s 2024 sales is pegged at $4.12 billion, indicating a 3.7{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} rise year over year.

The consensus mark for Hologic’s 2024 EPS is pegged at $3.99, indicating an increase of 7.6{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} from the year-ago period.

You can see the complete list of today’s Zacks #1 Rank stocks here. 

Price and Consensus: HOLX


Edwards Lifesciences: Headquartered in Irvine, CA, Edwards Lifesciences deals in products and technologies aimed at treating advanced cardiovascular diseases, especially structural heart disease in critically ill patients. Edwards Lifesciences expects to maintain its leadership position in the global Transcatheter Aortic Valve Replacement market through an increased focus on expanding patient access by actively leveraging current valve platforms for additional indications. This includes developing next-generation valve platforms, and maintaining trusted relationships with clinicians, payers and regulators. Edwards Lifesciences also remain committed to aggressively investing in structural heart disease and critical care technologies.

The Zacks Consensus Estimate for Edwards Lifesciences’ 2023 sales is pegged at $5.86 billion, indicating an 8.8{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} rise year over year. The same for Edwards Lifesciences’ adjusted earnings is pegged at $2.52 per share, an expected growth of 1.6{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} from 2022. Edwards Lifesciences carries a Zacks Rank #2 (Buy).

Price and Consensus: EW

IDEXX: Headquartered in Delaware, NJ, IDEXX is a developer, manufacturer and distributor of products and services primarily for the companion animal veterinary, livestock and poultry, water testing and dairy markets. The company is deriving strong top-line growth driven by continued benefits from the expansion of IDEXX’s global premium instrument installed base. CAG Diagnostics’ organic recurring revenue growth reflects solid gains across IDEXX’s major modalities globally, supported by growth in clinical service demand and expanded utilization of diagnostic products and services.

The consensus estimate for this Zacks Rank #2 company’s 2023 sales is pegged at $3.64 billion, indicating an 8{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} rise year over year. The same for IDEXX’s 2023 earnings is pegged at $9.51, an expected 18.4{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} growth from the year-ago period.

Price and Consensus: IDXX
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report

Edwards Lifesciences Corporation (EW) : Free Stock Analysis Report

Hologic, Inc. (HOLX) : Free Stock Analysis Report

IDEXX Laboratories, Inc. (IDXX) : Free Stock Analysis Report

To read this article on Zacks.com click here.

Zacks Investment Research

‘Load Up,’ Says Jim Cramer About These 2 ‘Strong Buy’ Healthcare Stocks

‘Load Up,’ Says Jim Cramer About These 2 ‘Strong Buy’ Healthcare Stocks

Versus a backdrop of soaring inflation, a slowing financial state and persistent price hikes, assessing the playbook for the coming yr, CNBC’s Jim Cramer claims it is extra important than at any time to glimpse at the earlier yr and see what worked. Basically, which stocks have managed to get over the bear conditions.

In the components of the S&P 500, electrical power and utilities have been segments that have overwhelmed the broader marketplace, and frequently speaking, so have those of the healthcare sector.

But health care shares, of class, are a diversified bunch, and operate the gamut from Big Pharma to medical center operators to health-related system makers to smaller biotechs nonetheless to notch any profits. Ideal now, however, says the Mad Revenue host, of all the stocks on supply, it is crystal clear what the current market needs.

“Wall Road likes rewarding companies with regular effects, awesome dividends and moderately valued stocks,” he explained. And the healthcare sector has some of these “boring, constant operators with low cost stocks” – these have been 2022’s winners. And these types of names are likely to preserve outperforming, according to Cramer.

With this in brain, let us search at two significant, reliable names Cramer thinks buyers should really be loading up on correct now. We have utilized the TipRanks databases to see whether the Street’s analysts concur with these picks. As it turns out, each and every inventory has been given sufficient bullish calls about the last three months to give it a “Strong Buy” consensus rating.

Humana Inc. (HUM)

If you are seeking for major, worthwhile, health care giants, then search no further. Humana, the initial Cramer pick, took the 41st place past year on the Fortune 500 list and is now the U.S.’s fourth biggest overall health insurance policies provider.

It also allows in the recent weather that the bulk of Humana’s revenues are produced from governing administration-sponsored applications, which offer the organization with a common and dependable money stream couple of can match. And in the complicated present-day climate that has been a genuine boon, as was distinct to see in the most up-to-date earnings report.

Q3 earnings grew by 10.16{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} year-above-12 months to $22.80 billion, boosted by an uptick in Medicare Benefit associates and rates. The bottom-line effectiveness was primarily extraordinary adj. EPS climbed by 42{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} compared to the exact interval final year, coming in at $6.88, significantly higher than the $6.28 envisioned by the analysts. Humana also introduced an accelerated $1 billion share buyback program, which is established to conclude in Q4.

Cramer calls HUM stock a “great turnaround tale,” and he is not on your own in his bullish outlook. Morgan Stanley analyst Michael Ha also sees the firm in a solid posture heading into 2023.

“We imagine Humana’s investments into 2023 has led to an unprecedented improvement in profit richness we have not traditionally witnessed from any conventional MA strategy (w/ current market share of at the very least 5{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f})… Wanting ahead, we do not see any swing components substance adequate to knock Humana off training course on 2023G EPS and believe that 2023 membership progress marks the commencing of an progressively highly effective multi-12 months earnings development story,” Ha opined.

To this end, Ha fees HUM shares an Obese (i.e., Invest in), backed by a $620 price target. How does this translate to investors? There’s upside of ~26{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} from present ranges. (To watch Ha’s observe document, click on below)

General, the Road is self-confident in Humana’s ongoing achievements one particular analyst prefers sitting down this just one out, but all 14 other modern reviews are favourable, naturally supplying the stock with a Powerful Invest in consensus ranking. At $622.73, the common concentrate on represents 1-year returns of ~23{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f}. (See Humana inventory forecast on TipRanks)

UnitedHealth Team (UNH)

Hardly any appear even larger or more trustworthy than the next Cramer-endorsed healthcare stock, which not for almost nothing he calls “best-of-breed.”

UnitedHealth is 1 of the world’s biggest earnings generators with a market place cap of $489 billion. Providing healthcare products and solutions and insurance coverage solutions, its functions are divided into two distinct segments UnitedHealthcare, which gives wellness insurance plan, and Optum, a company of information and technologies expert services.

As the primary player in a expanding worldwide wellbeing coverage industry, it’s no surprise to learn the stock has been able to outperform the S&P 500 in nine out of the previous 10 many years, 2022 included.

In the most not too long ago described quarter, for Q3, profits grew by 12{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} calendar year-more than-year to $80.9 billion, with equally Optum and UnitedHealthcare displaying double-digit expansion. Adj. EPS of $5.79 elevated by 28{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} from the exact same period of time a yr in the past, even though also beating the Street’s $5.43 forecast. The business also elevated its complete calendar year 2022 web earnings outlook.

On the dividend front, the present-day quarterly $1.65 payout yields a modest 1.26{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f}, but the dividend payout ratio will be approximately only 30{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} this yr. This gives the business a great deal of dollars for probable long term expansion assignments and to settle its personal debt. It could also permit the firm to hike the dividend in excess of the up coming few yrs.

This inventory has caught the consideration of 5-star analyst George Hill, from Deutsche Financial institution, who writes, “UNH has a very long monitor record of under-promising and about-providing… We carry on to see the business as the high-top quality defensive identify in the huge cap healthcare providers room supplied UNH’s expanding diversification into complementary businesses and the continued erosion of regulatory risks, which is mirrored in the high quality we granted in our goal numerous.”

All told, Hill fees UNH stock as a Buy while his $615 price tag target suggests shares will climb 17{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} greater more than the coming yr. (To view Hill’s monitor report, simply click below)

In general, other analysts also like what they are observing. 11 Purchases and 3 Holds insert up to a Powerful Obtain consensus ranking. Based mostly on the $602.64 common price tag target, the upside probable will come in at ~15{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f}. (See UnitedHealth stock forecast on TipRanks)

To come across very good ideas for shares investing at appealing valuations, check out TipRanks’ Best Shares to Invest in, a freshly released instrument that unites all of TipRanks’ fairness insights.

Disclaimer: The opinions expressed in this report are entirely those of the showcased analyst. The content material is intended to be employed for informational uses only. It is quite significant to do your individual evaluation in advance of creating any expenditure.

11 Best Medical Technology Stocks To Buy

11 Best Medical Technology Stocks To Buy

In this article, we discuss 11 best medical technology stocks to buy. If you want to see more stocks in this selection, check out 5 Best Medical Technology Stocks To Buy. 

The global medical devices market is expected to grow from $495.46 billion in 2022 to $718.92 billion by 2029 at a CAGR of 5.5{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} during the forecast period. Increasing investments in research and development by medical technology firms, combined with favorable policies and regulations, are anticipated to advance the medical device industry over the next few years.

Following the pandemic years, digital healthcare has become indispensable, and the medical technology industry has seen meaningful demand for online medical and AI-powered technology services. Companies in the digital healthcare space have witnessed their stocks rally despite economic turbulence. During the pandemic, seeing the accelerating demand for medtech treatment options, many conventional healthcare companies transformed themselves and offered technology-led health solutions to survive and gain market share. 

Some of the most popular medtech solutions include telemedicine, robotic surgery, medical imaging technologies, wearable medical devices, and AI-led healthcare management options. Investors seeking exposure to the medical technology sector can pick up stocks like DexCom, Inc. (NASDAQ:DXCM), Intuitive Surgical, Inc. (NASDAQ:ISRG), and Danaher Corporation (NYSE:DHR). 

Our Methodology 

We selected the following medical technology stocks based on positive analyst coverage, strong business fundamentals, and market visibility. We have assessed the hedge fund sentiment from Insider Monkey’s database of 920 elite hedge funds tracked as of the end of the third quarter of 2022. The list is arranged according to the number of hedge fund holders in each firm. 

Best Medical Technology Stocks to Buy

11. Stryker Corporation (NYSE:SYK)

Number of Hedge Fund Holders: 34

Stryker Corporation (NYSE:SYK) is a Michigan-based medical technology company that operates through two segments – MedSurg and Neurotechnology, and Orthopaedics and Spine. The company offers implants for use in joint replacements and trauma surgeries. Stryker Corporation (NYSE:SYK) also provides surgical equipment and surgical navigation systems, endoscopic and communications systems, emergency medical equipment, intensive care disposable products, and reprocessed and remanufactured medical devices. 

On December 7, Stryker Corporation (NYSE:SYK) declared a $0.75 per share quarterly dividend, a 7.9{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} increase from its prior dividend of $0.695. The dividend is payable on January 31, 2023 to shareholders of record on December 30. The dividend yield on December 19 came in at 1.25{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f}. 

Cowen analyst Joshua Jennings on December 14 raised the price target on Stryker Corporation (NYSE:SYK) to $283 from $233 and kept an Outperform rating on the shares. The analyst said the company looks positioned to provide positive 2023 revenue guidance on the back of a strong fourth quarter.

According to Insider Monkey’s data, 34 hedge funds were bullish on Stryker Corporation (NYSE:SYK) at the end of September 2022, compared to 46 funds in the prior quarter. Terry Smith’s Fundsmith LLP is the largest stakeholder of the company, with 5.6 million shares worth $1.14 billion.

Like DexCom, Inc. (NASDAQ:DXCM), Intuitive Surgical, Inc. (NASDAQ:ISRG), and Danaher Corporation (NYSE:DHR), Stryker Corporation (NYSE:SYK) is one of the premier medical technology stocks to consider. 

Diamond Hill Capital made the following comment about Stryker Corporation (NYSE:SYK) in its Q3 2022 investor letter:

“Stryker Corporation (NYSE:SYK) was the only new addition to the portfolio in Q3. It is one of the largest medical device manufacturers with a track record of consistently outgrowing its end markets and competitors. Stryker has a highly performance driven culture with a decentralized operating model that results in strong incentive alignment within the company. We believe the management team has executed well, making small but meaningful decisions that have positioned the firm well among competitors. Management operates with a market share gain mentality and strives to be a category leader in the market they are in. Stryker also benefits from its broad portfolio of surgical tools, small and large cap hospital equipment, waste management products, etc., which enables it to address all the needs of a hospital operating room and be a one-stop shop for health care facilities. This is particularly appealing to hospitals, and it positions Stryker to be the supplier of all operating room equipment versus a single product, thus enabling the company to gain market share.”

10. Inspire Medical Systems, Inc. (NYSE:INSP)

Number of Hedge Fund Holders: 37

Inspire Medical Systems, Inc. (NYSE:INSP) is a Minnesota-based medical technology company focused on the development and commercialization of minimally invasive solutions for patients with obstructive sleep apnea in the United States and internationally. It is one of the best medical technology stocks to invest in. 

On November 1, Inspire Medical Systems, Inc. (NYSE:INSP) reported a revenue of $109.2 million, up 77.0{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} year-over-year, beating Wall Street estimates by $14.59 million. Inspire Medical Systems, Inc. (NYSE:INSP) raised its full-year 2022 revenue guidance to between $384 million to $388 million, which would represent growth of 65{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} to 66{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} over the 2021 revenue of $233.4 million. This compares to the prior revenue guidance of $354 million to $362 million and a Wall Street estimate of $361.29 million.

Goldman Sachs analyst Amit Hazan upgraded Inspire Medical Systems, Inc. (NYSE:INSP) on December 13 to Buy from Neutral with a price target of $308, up from $245. Given “strong visibility” and the company’s “track record of execution,” the analyst sees upside to present consensus and expects “strong” upcoming 2023 guidance. Given multiple compression over the last six months relative to the group, the shares now offer improved better risk/reward, added the analyst, who categorized Inspire Medical Systems, Inc. (NYSE:INSP) as his top Medtech midcap for 2023.

According to Insider Monkey’s data, Inspire Medical Systems, Inc. (NYSE:INSP) was part of 37 hedge fund portfolios at the end of Q3 2022, compared to 31 in the prior quarter. Andreas Halvorsen’s Viking Global held the largest stake in the company, comprising 633,572 shares worth $112.3 million. 

Here is what Alger Capital specifically said about Inspire Medical Systems, Inc. (NYSE:INSP) in its Q2 2022 investor letter:

“Inspire Medical Systems, Inc. (NYSE:INSP) markets the only FDA-approved implantable neuromodulation device used to treat obstructive sleep apnea (OSA). Inspire’s device monitors a patient’s breathing and delivers electrical stimulation to the hypoglossal nerve in order to maintain an open airway.

We believe the second quarter underperformance of Inspire shares is primarily attributable to the rotation away from high-growth, high-valuation health care names that are currently unprofitable. Additionally, we think the underperformance was compounded by Inspire being one of the best-performing medical device stocks in the first quarter. We believe many investors have been “selling the winners” in a risk-off environment. Looking ahead, we continue to believe that Inspire is one of the best growth opportunities in medical devices with no anticipated immediate competition. We also believe its market is highly underpenetrated.”

9. Align Technology, Inc. (NASDAQ:ALGN)

Number of Hedge Fund Holders: 38

Align Technology, Inc. (NASDAQ:ALGN) is an Arizona-based medical device company that designs, manufactures, and markets Invisalign clear aligners and iTero intraoral scanners and services for restorative and aesthetic dentistry. On October 31, Align Technology, Inc. (NASDAQ:ALGN) announced an accelerated stock repurchase agreement with Goldman Sachs to repurchase $200 million of its common stock as part of the $1 billion share repurchase program disclosed in May. The transaction will be funded with cash on hand and is expected to conclude by February 1, 2023. Align Technology, Inc. (NASDAQ:ALGN) is one of the premier medical technology stocks to monitor. 

On October 27, Stifel analyst Jonathan Block maintained a Buy recommendation on Align Technology, Inc. (NASDAQ:ALGN) but lowered the price target on the shares to $265 from $325. Following the company’s Q3 results and guidance, 2022 and 2023 EBITDA and EPS estimates are likely to “come toppling down,” said the analyst. Now, investors “will have to decide if the tables could turn in coming quarters,” noted Block, who added that comps will ease, innovation should improve, and that Align Technology, Inc. (NASDAQ:ALGN)’s market share “seems to be relatively resilient.”

According to Insider Monkey’s data, 38 hedge funds were bullish on Align Technology, Inc. (NASDAQ:ALGN) at the end of September 2022, compared to 33 funds in the last quarter. Brian Bares’ Bares Capital Management is the largest position holder in the company, with 913,324 shares worth over $189 million. 

Here is what Polen Global Growth has to say about Align Technology, Inc. (NASDAQ:ALGN) in its Q2 2022 investor letter:

“Align Technology shares declined significantly during the second quarter when management reported a meaningful deceleration in growth. Management cited a host of challenges, including COVID19 impacts, especially in China with restrictions and lockdowns under their zero-COVID policy, a weaker economic environment, inflationary pressures, supply chain disruptions, and the war in Ukraine, to name a few. Tough comparisons were also a reality — Invisalign case starts in 1Q22 were roughly flat, having lapped the 66{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} growth from the prior year. It’s not completely surprising that growth is slowing on such tough comparisons, but the company’s shares declined on the news.

By looking at Align’s three-year compound average growth rate (CAGR) to smooth out the ups and downs through COVID, key metrics like Invisalign case shipment, clear aligner revenue, and earnings per share have all grown ~20{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} during the trailing three years. We think this is quite respectable given the challenges during this period, but the lack of near-term momentum or visibility has not been well received in the current environment. According to our research, Align is the clear market leader, has global scale, a superior product, and still very modest market penetration. While growth may be challenged near term, we remain confident in the long-term growth opportunity.”

8. Veeva Systems Inc. (NYSE:VEEV)

Number of Hedge Fund Holders: 42

Veeva Systems Inc. (NYSE:VEEV) is a California-based company that provides cloud-based software for the life sciences industry in North America, Europe, the Asia Pacific, the Middle East, Africa, and Latin America. The company offers customer relationship management and data management applications for the medical industry. It is one of the premier medical technology stocks to monitor. 

On December 1, Veeva Systems Inc. (NYSE:VEEV) reported a Q3 non-GAAP EPS of $1.13 and a revenue of $552.35 million, outperforming Wall Street estimates by $0.06 and $6.29 million, respectively. Non-GAAP operating income for the third quarter was $219.5 million, compared to $199.4 million a year ago, representing an increase of 10{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} year-over-year.

KeyBanc analyst Scott Schoenhaus on December 5 maintained an Overweight rating on Veeva Systems Inc. (NYSE:VEEV) but lowered the price target on the shares to $210 from $220 to reflect some multiple impairment as the company works toward moving its CRM business from Salesforce to its Vault Platform when the contract expires in September 2025. The analyst noted the company posted a strong quarter with top and bottom-line beats, but guided slightly below expectations on Q4 billings, revenue, and operating profits.

According to Insider Monkey’s third quarter database, 42 hedge funds were long Veeva Systems Inc. (NYSE:VEEV), compared to 45 funds in the prior quarter. Greg Poole’s Echo Street Capital Management is the largest position holder in the company, with 899,876 shares worth $148.3 million. 

Here is what Artisan Partners specifically said about Veeva Systems Inc. (NYSE:VEEV) in its Q2 2022 investor letter:

“Veeva Systems Inc. (NYSE:VEEV) is one of the highest quality franchises in our portfolio. The company has the dominant CRM platform for pharmaceutical sales and marketing organizations, and it is replicating that success with the rollout of numerous other modules focused on pharmaceutical customers’ manufacturing, quality, safety and clinical operations. Growth has temporarily slowed over the past year as the company laps difficult YoY comparisons caused by the rapid adoption of their virtual sales call solution during the pandemic. Several large deals also encountered unexpected delays in late 2021. Despite these short-term headwinds, we remain confident in Veeva’s future growth prospects and high-quality business model (~40{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} free cash flow margins supported by largely recurring subscription revenues). Meanwhile, we believe the defensive nature of its end market (health care) and strategic importance of cloud IT driven transformations could help buffer the company against a weaker global economy. As shares declined in Q2 along with other software stocks, we added to our position.”

7. Bio-Rad Laboratories, Inc. (NYSE:BIO)

Number of Hedge Fund Holders: 45

Bio-Rad Laboratories, Inc. (NYSE:BIO) is one of the best medical technology stocks to consider buying. The California-based company manufactures and distributes life science research and clinical diagnostic products in the United States, Europe, Asia, Canada, and Latin America. Bio-Rad Laboratories, Inc. (NYSE:BIO) focuses on selected segments of the life sciences market such as proteomics, genomics, biopharmaceutical production, cellular biology, and food safety. It is one of the leading medical technology stocks to buy. 

On December 6, RBC Capital analyst Conor McNamara initiated coverage of Bio-Rad Laboratories, Inc. (NYSE:BIO) with an Outperform rating and a $565 price target. He believes shareholders will benefit from “an extended period of multiple expansion” as the company continues to deliver revenue acceleration and margin improvement. The stock trades at a 60{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f}-70{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} discount to peers and with $200 per share in cash and investments has “the most balance sheet optionality of any company in our sector,” the analyst noted.

According to Insider Monkey’s data, 45 hedge funds were bullish on Bio-Rad Laboratories, Inc. (NYSE:BIO) at the end of the third quarter of 2022, compared to 43 funds in the prior quarter. Israel Englander’s Millennium Management is the biggest position holder in the company, with 458,645 shares worth $191.3 million. 

6. Medtronic plc (NYSE:MDT)

Number of Hedge Fund Holders: 55

Medtronic plc (NYSE:MDT) develops, manufactures, and commercializes device-based medical therapies to healthcare systems, physicians, clinicians, and patients worldwide. The company operates through Cardiovascular Portfolio, Medical Surgical Portfolio, Neuroscience Portfolio, and Diabetes Operating Unit segments. On December 8, Medtronic plc (NYSE:MDT) declared a quarterly dividend of $0.68 per share, in line with previous. The dividend is payable on January 13, 2022 to shareholders of record on December 21. The dividend yield on December 19 came in at 3.55{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f}. 

On November 30, Wells Fargo analyst Larry Biegelsen maintained an Equal Weight rating on Medtronic plc (NYSE:MDT) and trimmed the firm’s price target on the shares to $77 from $82. The analyst updated his 2024 and forward EPS forecast for Medtronic plc (NYSE:MDT), as he factored in the FX impact on EPS.

According to Insider Monkey’s third quarter database, 55 hedge funds were bullish on Medtronic plc (NYSE:MDT), compared to 54 funds in the earlier quarter. Peter Rathjens, Bruce Clarke, and John Campbell’s Arrowstreet Capital is the largest stakeholder of the company, with 7.16 million shares worth $578.30 million. 

Like DexCom, Inc. (NASDAQ:DXCM), Intuitive Surgical, Inc. (NASDAQ:ISRG), and Danaher Corporation (NYSE:DHR), Medtronic plc (NYSE:MDT) is one of the best medical technology stocks to invest in. 

Here is what Artisan Partners specifically said about Medtronic plc (NYSE:MDT) in its Q2 2022 investor letter:

“While Medtronic plc (NYSE:MDT)’s procedure volumes recovered to pre-COVID levels, foreign exchange headwinds overshadowed underlying business value growth, and supply chain issues, including those related to China’s lockdowns, impacted the surgical innovations business. The downdraft in the market during the quarter led to a pile-on. We are being patient with our investment in Medtronic because the company continues to be a strong free cash flow generator and is attractively priced, with a FCF yield of 5{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} on trailing one-year numbers and a dividend yield of 3{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f}. Medtronic is under new management that is focused on growing the company’s top line, reinvesting in R&D, returning cash to shareholders and growing operating profits. We like new management’s strategy and believe new product launches, increased surgery visits, sound M&A transactions and a shareholder returns focus, should reinvigorate the business. We added to our positions in these health care names during the quarter.”

Click to continue reading and see 5 Best Medical Technology Stocks To Buy. 

Suggested articles:


Disclosure: None. 11 Best Medical Technology Stocks To Buy is originally published on Insider Monkey.

13 Best Medical Device Stocks To Buy Now

13 Best Medical Device Stocks To Buy Now

In this article, we will discuss the 13 Best Medical Device Stocks To Buy Now. You can skip our detailed analysis of the Medical Device Industry and go directly to the 5 Best Medical Device Stocks To Buy Now.

Just like every other industry, the medical device industry has seen tremendous technological advancement over the past two decades. Medical devices are essential and have become a fundamental part of the healthcare system as they provide a more effective and efficient way of preventing, diagnosing, and treatment for illnesses and diseases.

After the outbreak of COVID-19, the medical device industry grew by 10-14{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f}, whereas in the period leading up to the pandemic (2017-2019), it only witnessed a growth of around 4{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f}. COVID-19 created new demand for medical device products, and the medical technology sector came up with new solutions using technologies like artificial intelligence (AI), machine learning, 3d printing, etc., to tackle the challenges created by the pandemic.

Some developed countries even started working on medical robots to compensate for the shortage of nurses worldwide. According to the COVID-19 Two-Year Impact Survey conducted by The American Nurses Foundation, in the United States, almost 52{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} of nurses thought of leaving their jobs due to heavy workloads and burnout. The implementation of advanced technologies in the healthcare sector has provided the medical device industry a huge boost even during the pandemic. Just like every other business sector, the medical tech sector also faced issues relating to supply chain disruption, but this period also provided an opportunity for growth for the medical device industry.

According to Statista, in 2022, the medical technology market revenue is projected to reach $575.80 billion. The market’s biggest sector, the medical devices sector, is also forecasted to reach a market volume of $455.10 billion in 2022. Forecasted to grow at a CAGR of 5.95{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} during 2022-2027, the global medical technology market is forecasted to reach $768.80 billion by 2027.

smart.art/Shutterstock.com

Our Methodology

We scanned Insider Monkey’s database of over 900 hedge funds and picked the most popular medical device stocks among these funds. Wall Street analysts are also bullish on most of these stocks.

13. Varex Imaging Corporation (NASDAQ:VREX)

Forward P/E ratio as of December 10: 28.17

Number of Hedge Fund Holders: 15

Varex Imaging Corporation (NASDAQ:VREX) engages in the designing and manufacturing of components used in X-ray imaging. The company’s research and manufacturing operations run through the United States, Europe, China, and the Philippines. The company’s operations are divided into two segments. The medical segment generates the majority of revenue and deals in components such as X-ray tubes, digital flat panel image detectors, ionization chambers, high-voltage connectors, etc. The industrial sector manufactures and sells Linatron X-ray accelerators.

On October 12, 2022, Young Li, an analyst at Jefferies, began covering Varex Imaging Corporation (NASDAQ:VREX) with a price target of $24 and a Hold rating. The analyst believes that the present macro environment is difficult for the company and its customers due to persistent inflation and supply chain challenges.

According to Insider Monkey’s database, 15 hedge funds had stakes in Varex Imaging Corporation (NASDAQ:VREX) at the end of the September quarter. Pzena Investment Management remained the leading stakeholder of the company at the end of the third quarter.

In addition to Varex Imaging Corporation (NASDAQ:VREX), InMode Ltd. (NASDAQ:INMD), Pro-Dex, Inc. (NASDAQ:PDEX), and Sensus Healthcare, Inc. (NASDAQ:SRTS) are included in our list of 13 best medical device stocks to buy now.

12. Abbott Laboratories (NYSE:ABT)

Forward P/E ratio as of December 10: 24.15

Number of Hedge Fund Holders: 62

Founded in 1888, Abbott Laboratories (NYSE:ABT) manufactures and markets medical devices including diagnostic equipment and testing kits. Almost 60{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} of the company’s revenue is generated from sales outside of the United States.

On October 20, 2022, Shagun Singh, an analyst at RBC Capital, reduced his price target on Abbott Laboratories (NYSE:ABT) to $126 while keeping an Outperform rating on the stock. The analyst decreased his price target after the company’s Q3 results, as core growth slowed down during the quarter.

As per Insider Monkey’s database, 62 hedge funds remained bullish on Abbott Laboratories (NYSE:ABT) at the end of Q3 2022. Fisher Asset Management came out to be the biggest holder of the company’s shares at the end of the quarter.

Diamond Hill Capital made the following comment about Abbott Laboratories (NYSE:ABT) in its Q3 2022 investor letter:

Also among our bottom contributors were health care products manufacturer Abbott Laboratories (NYSE:ABT), global pharmaceutical company Pfizer, media and technology giant Alphabet, and insurance company American International Group (AIG).

Abbott has been working through a recall of its infant formula brand Similac in the US, which has continued to pressure its share price. Although the recall will impact near-term revenues, we are not concerned about any long-term impacts. We remain optimistic about the company given it is one of the highest quality names in health care, in our view, with a talented management team that makes smart capital allocation decisions. Abbott also has leading health care and consumer franchises with a particularly strong competitive position in its medical device business. The company continues to launch innovative products in key strategic areas (such as diabetes, structural heart, and diagnostics), which should help drive not only revenue growth but margin expansion.

11. Teleflex Incorporated (NYSE:TFX)

Forward P/E ratio as of December 10: 17.39

Number of Hedge Fund Holders: 23

Headquartered in Pennsylvania, United States, Teleflex Incorporated (NYSE:TFX) manufactures hospital supplies and devices with a primary focus on bloodstream/vascular and surgical areas. The company operates in seven segments that include vascular access (generating 25{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} of the total revenue in 2021), interventional, interventional urology, surgical, anesthesia, original equipment, and the rest of the products. The company’s 60{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} of sales come from the domestic market.

On October 28, 2022, David Turkaly, an analyst from JMP Securities, reduced his price target on Teleflex Incorporated (NYSE:TFX) to $330 while keeping an Outperform rating on the stock. According to the analyst, Teleflex Incorporated (NYSE:TFX) has faced several challenges this year, including supply chain issues and labor shortages. However, the company is now well-positioned to address the issues at hand.

23 hedge funds were long on the company’s stock at the end of the third quarter, according to Insider Monkey’s database. Citadel Investment Group had the biggest long position in the company at the end of Q3 2022.

10. QuidelOrtho Corporation (NASDAQ:QDEL)

Forward P/E ratio as of December 10: 18.69

Number of Hedge Fund Holders: 29

QuidelOrtho Corporation (NASDAQ:QDEL) deals with the development, manufacturing, and marketing of diagnostic healthcare products. The product portfolio of the company includes point-of-care tests for diseases such as critical cardiac health, autoimmune biomarkers, and other infectious diseases. QuidelOrtho Corporation (NASDAQ:QDEL) is also engaged in producing clinical and at-home COVID-19-detecting products.

On December 6, 2022, RBC Capital analyst Conor McNamara started covering QuidelOrtho Corporation (NASDAQ:QDEL) with a price target of $125, and an Outperform rating. Conor McNamara believes that following the pandemic, the company will have a more diverse regional and product footprint and a larger market share in more lucrative end markets.

At the end of Q3 2022, 29 hedge funds in Insider Monkey’s database were long QuidelOrtho Corporation (NASDAQ:QDEL) at the end of the quarter. Birchview Capital remained the leading stakeholder of the company at the end of Q3 2022

Meridian Funds made the following comment about QuidelOrtho Corporation (NASDAQ:QDEL) in its Q3 2022 investor letter:

QuidelOrtho Corporation (NASDAQ:QDEL) is a global leader in the diagnostics industry. The merger of Quidel and Ortho Clinical Diagnostics has resulted in a top 10 player in the in-vitro diagnostics industry, combining Quidel’s strong point of care platform with Ortho’s blood chemistry and transfusion platform. We believe the new company will be much more consistent in its ability to deliver steady top-line growth at attractive margins to fuel free cash flow growth. Further boosting our conviction in QuidelOrtho is its robust product pipeline. Pipeline developments include the company’s Savanna platform, which solves a long-term need for near-patient molecular testing that is accurate, fast, and economical. We believe the stock weakness is due to the anticipated decline in COVID-19 testing. However, we believe the long-term earnings and free cash flow profile are underappreciated, and as a result we increased our position in the stock.

9. Zimmer Biomet Holdings, Inc. (NYSE:ZBH)

Forward P/E ratio as of December 10: 17.92

Number of Hedge Fund Holders: 37

Zimmer Biomet Holdings, Inc. (NYSE:ZBH) manufactures and markets orthopedic reconstructive implants and orthopedic surgical equipment. After acquiring Centerpulse in 2003 and Buimet in 2015, Zimmer Biomet Holdings, Inc. (NYSE:ZBH) is now leading the reconstructive market in the US, Europe, and Japan.

On November 23, 2022, Larry Biegelsen, an analyst at Wells Fargo, upgraded his rating on Zimmer Biomet Holdings, Inc. (NYSE:ZBH) to Equal Weight with a price target of $124. The analyst believes the company is showing strong growth in the ortho market, which should drive upside in the stock.

As per Insider Monkey’s database, 37 funds remained bullish on the company at the end of Q3 2022. Citadel Investment Group had the biggest long position on the company’s shares at the end of the third quarter.

8. NuVasive, Inc. (NASDAQ:NUVA)

Forward P/E ratio as of December 10: 17.70

Number of Hedge Fund Holders: 25

NuVasive, Inc. (NASDAQ:NUVA) engages in minimally invasive surgical devices. The company’s specialty is in its solutions and devices for spine surgery. These devices offer a  surgical platform that minimizes soft-tissue damage and contact with vital nerves while maximizing visibility during spine fusion surgery. Other products include biologics that help in spinal fusion and in the process of bone healing. NuVasive, Inc. (NASDAQ:NUVA) maximum revenue is generated from the United States via its spine surgery products.

On November 10, 2022, Joshua Jennings, an analyst at Cowen, reduced his price target on NuVasive, Inc. (NASDAQ:NUVA) to $50 while keeping an Outperform rating on the stock. According to the analyst, the growth of key products like Simplify and Pulse should continue to help drive strong performance in the future.

According to Insider Monkey’s database, 25 hedge funds held stakes in NuVasive, Inc. (NASDAQ:NUVA) at the end of the third quarter ending September 2022. Citadel Investment Group remained the leading stakeholder in the company at the end of Q3 2022.

7. Integra LifeSciences Holdings Corporation (NASDAQ:IART)

Forward P/E ratio as of December 10: 15.65

Number of Hedge Fund Holders: 26

Integra LifeSciences Holdings Corporation (NASDAQ:IART) is a medical equipment company based in New Jersey. The company develops products for regenerative therapy, neurosurgical applications, and extremity orthopedics. Although the company sells its products worldwide, the majority of its revenue comes from domestic sales.

On October 27, 2022, David Turkaly, an analyst at JMP Securities, reduced his price target on Integra LifeSciences Holdings Corporation (NASDAQ:IART) to $75 from $85 while keeping an Outperform rating on the stock. The analyst believes that the improvement in the company’s volumes will counterbalance the currency headwinds and persisting supply problems.

As per Insider Monkey’s database, 26 hedge funds owned stakes in Integra LifeSciences Holdings Corporation (NASDAQ:IART) at the end of the September quarter.  Arrowstreet Capital was the most bullish fund on the company’s stock at the end of Q3 2022.

6. Smith & Nephew plc (NYSE:SNN)

Forward P/E ratio as of December 10: 16.08

Number of Hedge Fund Holders: 12

Smith & Nephew plc (NYSE:SNN) is a UK-based company that engages in the manufacturing and marketing of orthopedic devices, arthroscopic technologies, sports medicines, and wound-care solutions. The United States market is responsible for almost half of the total revenue, while only over 30{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} of the total sale comes from other developed markets. The orthopedic products drive almost 42{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} of the company’s total revenue.

On November 9, 2022, Robert Davies, an analyst at Morgan Stanley, reduced his price target on Smith & Nephew plc (NYSE:SNN) to £1,217 from £1,229 while keeping an Equal Weight rating on the stock.

According to Insider Monkey’s database, 12 hedge funds held shares of the company at the end of the third quarter of 2022. Arrowstreet Capital was the most bullish fund on the company’s stock at the end of Q3 2022.

Click to continue reading and see 5 Best Medical Device Stocks To Buy Now.

Suggested Articles:

Disclosure: None. 13 Best Medical Device Stocks To Buy Now is originally published on Insider Monkey.

Wall Street’s favorite stable stocks include a health care name that can rally nearly 60{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f}

Wall Street’s favorite stable stocks include a health care name that can rally nearly 60{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f}

2 Best Healthcare Stocks to Buy Right Now

2 Best Healthcare Stocks to Buy Right Now

Couple of sectors are as resilient in unsure environments as health care. This is mainly because medicines and wellness coverage are necessary to the well-becoming of sufferers. Basically put, men and women need them. And supplied the increasing worldwide geriatric populace, you can find cause to consider that these health care items will become even extra indispensable around time.

Health and fitness insurance company Elevance Overall health (ELV -1.05{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f}) and pharmaceutical corporation Novartis (NYSE: NVS) are two dominant health care stocks to think about obtaining as a play on the inelasticity of the sector.

A patient speaks with their doctor at an appointment.

Picture supply: Getty Illustrations or photos.

1. Elevance Health and fitness

If you haven’t heard of Elevance Wellness, that’s due to the fact it used to be identified as Anthem — right until rebranding underneath its new moniker in March. By both title, it truly is a sizable firm with 47.1 million clinical associates and yet another 22.6 million who have signed up for lifetime, disability, dental, eyesight, and Medicare Section D protection.

For context, the firm’s $113 billion industry capitalization tends to make it the second-major pure-participate in wellbeing insurance provider driving UnitedHealth Team‘s (NYSE: UNH) market cap of $471 billion. And specified the encouraging outlook of the world wide wellness insurance plan industry, this is one of the best industries in which a enterprise could be an recognized leader. 

That’s mainly because of the expanding geriatric populace, which needs a superior degree of checking and health care treatment. Somewhere around 10{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} of the world population is in excess of the age of 65, which is normally categorized as geriatric.  This is a massive part of why the global overall health coverage marketplace could mature 4.6{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} every year from $2.8 trillion in 2020 to $3.9 trillion by 2027, in accordance to market study business Global Market place Insights. 

Elevance transformed its $76.7 billion in initially-half profits into $3.5 billion in net earnings. This is equal to a 4.5{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} web margin, which demonstrates that the well being insurance provider is a profitable small business.  That’s why analysts imagine Elevance will capitalize on the expanding demand from customers for health and fitness coverage with 11.9{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} yearly earnings progress above the following 5 yrs. For context, which is just a minimal underneath the health care ideas field average once-a-year earnings expansion projection of 12.6{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f}. 

The firm’s 1.1{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} dividend yield is reasonably decrease than the S&P 500 index’s 1.6{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} yield. But with the dividend payout ratio projected to appear in underneath 18{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} in 2022, the health and fitness insurer’s dividend progress really should make up for its decrease starting off generate. This describes why I imagine that Elevance Health’s dividend will grow at an annualized fee in the teenagers for the following five to 10 years. 

Most effective of all, the overall health insurance company can be acquired at a ahead cost-to-earnings (P/E) ratio of 14.8. This is somewhat below the business typical of 16.1, which tends to make Elevance Health a persuasive prosperity compounder to invest in. 

2. Novartis

Thanks to an aging inhabitants and new drug launches to treat scarce disorders, the worldwide pharmaceutical marketplace is forecast to enhance from $1.4 trillion in 2021 to $1.8 trillion in 2026. As a person of the most significant players in the environment, Switzerland-based Novartis will no doubt benefit from this trend. 

The company’s portfolio is composed of 13 medicines that are on track to produce at minimum $1 billion in income for 2022. These include the immunology medicine Cosentyx and the heart failure medicine Entresto, which place up $2.4 billion and $2.2 billion in first-50 {08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} gross sales with double-digit growth premiums, respectively.  This amazing drug portfolio is how analysts are anticipating $52.4 billion in revenue from Novartis for this 12 months. 

And with 150 projects currently in distinctive phases of clinical advancement, the firm’s long term appears to be promising. Long term drug launches will extra than offset the reduction of income from forthcoming patent expirations, which is why analysts are predicting 4.1{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} once-a-year earnings advancement by way of the next five a long time.

Novartis’ 4.1{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f} dividend produce is almost triple the S&P 500 index’s generate. With the ahead payout ratio projected to appear in just beneath 50{08cd930984ace14b54ef017cfb82c397b10f0f7d5e03e6413ad93bb8e636217f}, the enterprise must have no issue in elevating its dividend even further in the decades to arrive. 

And buyers looking for passive earnings can snatch up shares of Novartis at a forward P/E ratio of 12.3, which is just above the market regular of 10.7 — and rarely an unreasonable premium to fork out for a earth-class pharma stock this sort of as Novartis.